
THE VR FORECASTER – ANNUAL FORECAST MODEL
ORDER TODAY AND WE WILL MANUALLY EMAIL YOU THE REPORT BEFORE IT IS POSTED ON THE WEBSITE
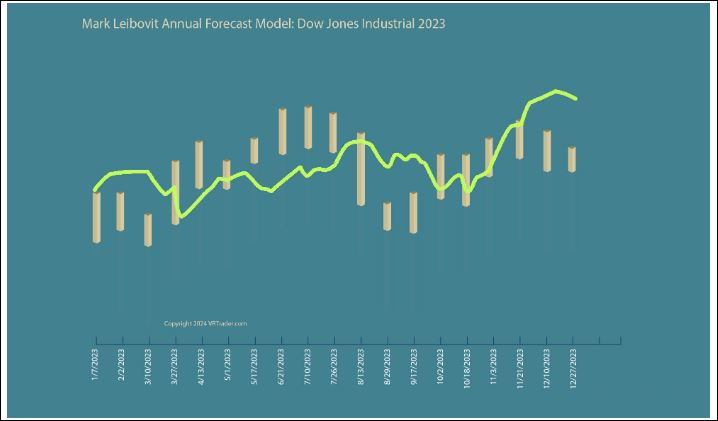
HERE IS THE 2023 ANNUAL FORECAST MODEL WITH THE ‘RESULTS’ SUPERIMPOSED
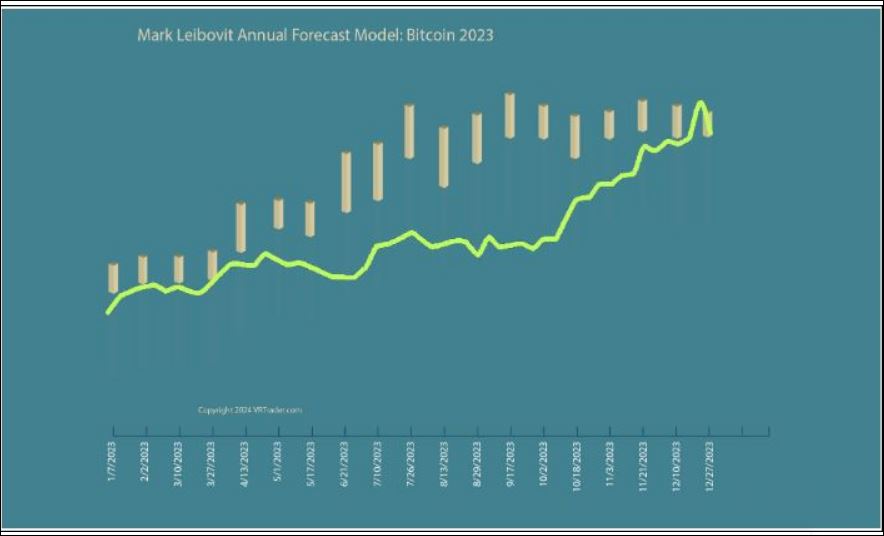
HERE IS THE 2023 ANNUAL FORECAST MODEL FOR BITCOIN WITH THE ‘RESULTS’ SUPERIMPOSED
ORDER PAGE
http://tinyurl.com/5f7wb6zs
FORMER AFC CHAMPS KANSAS CITY FORTELLS A BEAR MARKET!


https://www.howestreet.com/2024/02/is-the-stock-market-too-hot-mark-leibovit
U.S. Stocks Move Sharply Lower On Hotter-Than-Expected Inflation Data
Stocks moved sharply lower during trading on Tuesday, with the major averages all showing significant moves to the downside after ending Monday’s trading narrowly mixed. The Dow pulled back well off yesterday’s record closing highs.
The major averages climbed off their worst levels going into the close but still posted steep losses on the day. The Dow tumbled 524.63 points or 1.4 percent to 38,272.75, the Nasdaq plunged 286.95 points or 1.8 percent to 15,655.60 and the S&P 500 slumped 68.67 points or 1.4 percent to 4,953.17.
The sell-off on Wall Street came following the release of a highly anticipated Labor Department report showing consumer prices in the U.S. increased by slightly more than expected in the month of January.
The Labor Department said its consumer price index rose by 0.3 percent in January after inching up by 0.2 percent in December. Economists had expected consumer prices to edge up by 0.2 percent.
While the report also showed the annual rate of consumer price growth slowed to 3.1 percent in January from 3.4 percent in December, economists had expected the pace of growth to slow to 2.9 percent.
Excluding food and energy prices, core consumer prices climbed by 0.4 percent in January after rising by 0.3 percent in December. Core prices were expected to increase by 0.3 percent.
The annual rate of core consumer price in January came in unchanged from the previous month at 3.9 percent. The pace of core price growth was expected to decelerate to 3.7 percent.
With Federal Reserve officials repeatedly saying they need more “confidence” inflation is slowing before lowering interest rates, the data has further reduced optimism about a near-term rate cut.
CME Group’s FedWatch Tool is currently indicating just an 8.5 percent chance of a quarter point rate cut in March, while the chances of a quarter point rate cut in early May have fallen to 33.5 percent.
Quincy Krosby, Chief Global Strategist for LPL Financial, called the report a “disappointment for those who expected inflation to edge lower allowing the Fed to begin easing rates sooner rather than later.”
“This report underscores the Fed’s messaging that they’ll need more information specifically inflation-related data before a policy transition,” Krosby said. “The ‘last mile’ – as expected – is proving to be stickier and more stubborn inhibiting even the most dovish wing of the FOMC.”
Treasuries yields surged in response to the data, with the yield on the benchmark ten-year note reaching its highest levels in two months.
Sector News
Gold stocks saw substantial weakness on the day, dragging the NYSE Arca Gold Bugs Index down by 6.5 percent to a four-month closing low.
The sell-off by gold stocks came amid a steep drop by the price of the precious metal, with gold for April delivery tumbling $25.80 to $2,007.20 an ounce.
Significant weakness was also visible among networking stocks, which pulled back sharply after surging in the previous session. After jumping by 2.5 percent during Monday’s trading, the NYSE Arca Networking Index plunged by 4.4 percent.
Interest rate-sensitive housing stocks also saw considerable weakness, resulting in a 3.2 percent nosedive by the Philadelphia Housing Sector Index.
Tobacco, steel, banking and telecom stocks also moved notably lower amid broad based weakness on Wall Street.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region turned in a mixed performance on Tuesday, with markets in Hong Kong and mainland China still closed for holidays. Japan’s Nikkei 225 Index surged by 2.9 percent, while Australia’s S&P/ASX 200 Index dipped by 0.2 percent.
Meanwhile, the major European markets all moved to the downside on the day. While the German DAX Index slumped by 0.9 percent, the French CAC 40 Index and the U.K.’s FTSE 100 Index both slid by 0.8 percent.
In the bond market, treasuries moved sharply lower in reaction to the U.S. inflation data. Subsequently, the yield on the benchmark ten-year note, which moves opposite of its price, spiked 14.4 basis points to 4.316 percent.
Looking Ahead
A relatively quiet day on the U.S. economic front may lead to light trading on Wednesday ahead of an avalanche of data on Thursday.
CHINESE NEW YEAR

FOMC MEETINGS 2024
MARCH 20
MAY 1
JUNE 12
JULY 31
SEPT 18
NOV 7
DEC 18

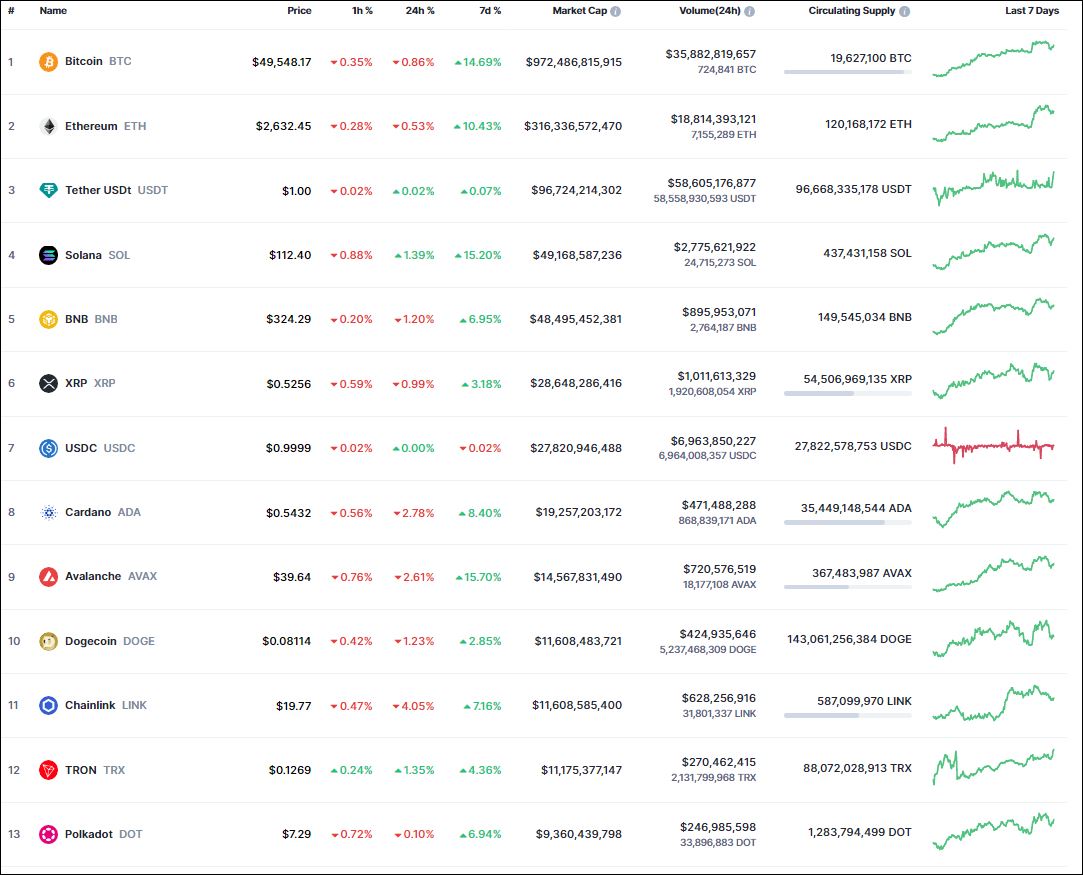
CRYPTO UPDATE AS OF FEBRUARY 13, 2024:



https://tinyurl.com/2rd9wv52
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
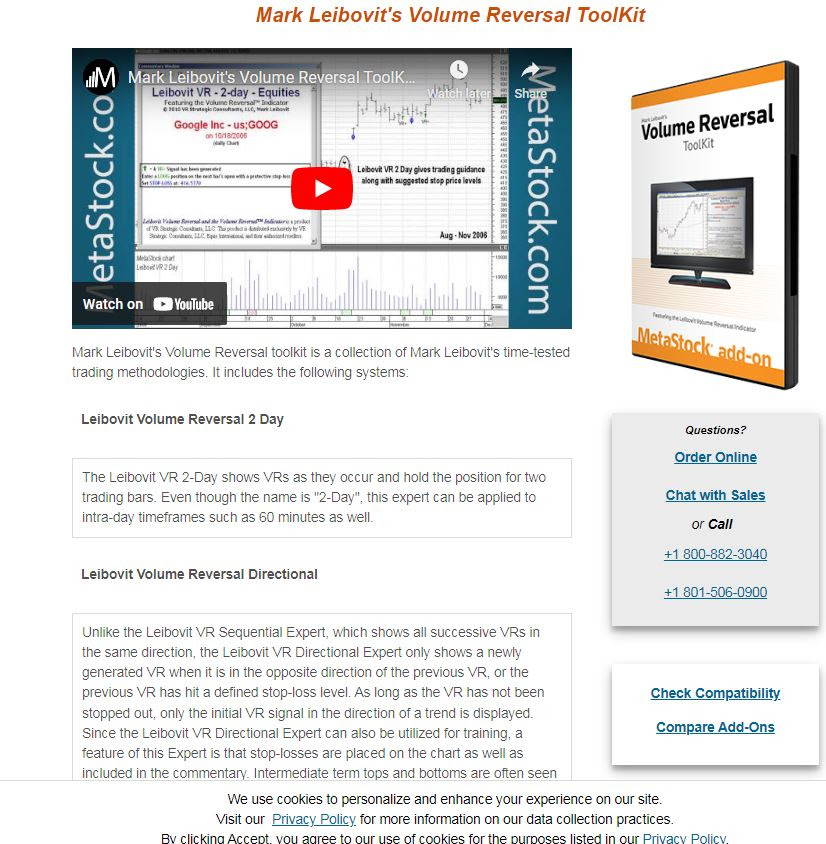
https://www.metastock.com/prod


COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.


[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]