

GENERAL NEWS:
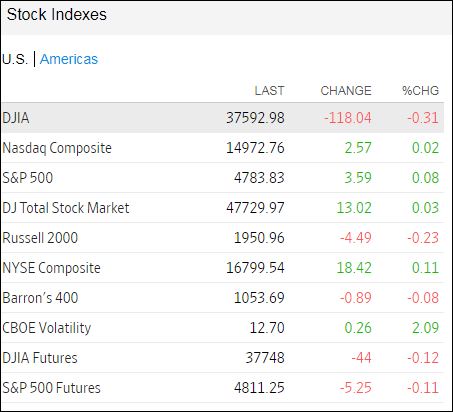
With traders digesting earnings news from several big-name companies as well as the latest U.S. inflation data, stocks fluctuated over the course of the trading session on Friday.
While the S&P 500 and the Nasdaq eventually ended the session slightly higher, the narrower Dow showed a modest move to the downside.
The S&P 500 inched up 3.59 points or 0.1 percent to 4,783.83 and the Nasdaq crept up 2.57 points or less than a tenth of a percent to 14,972.76, the Dow dipped 118.04 points or 0.3 percent to 37,592.98.
For the week, the tech-heavy Nasdaq spiked by 3.1 percent, the S&P 500 jumped by 1.8 percent and the Dow rose by 0.3 percent.
A steep drop UnitedHealth (UNH) weighed on the Dow, with the health insurance giant tumbling by 3.4 percent despite reporting fourth quarter results that beat analyst estimates on both the top and bottom lines.
Financial giants Bank of America (BAC), Wells Fargo (WFC) and JPMorgan Chase (JPM) also moved to the downside after reporting their quarterly results, while Citigroup (C) moved higher over the course of the session.
Traders were also reacting to a Labor Department report showing producer prices in the U.S. unexpectedly edged slightly lower in the month of December.
The Labor Department said its producer price index for final demand slipped by 0.1 percent in December, matching a revised dip in November.
Economists had expected producer prices to inch up by 0.1 percent compared to the unchanged reading originally reported for the previous month.
Meanwhile, the report said the annual rate of producer price growth accelerated to 1.0 percent in December from a downwardly revised 0.8 percent in November.
The annual rate of producer price growth was expected to speed up to 1.3 percent from the 0.9 percent originally reported for the previous month.
After Thursday’s report showing consumer prices in the U.S. rose by slightly more than expected in the month of December, the wholesale price data added to recent uncertainty about the outlook for interest rates.
“PPI reports always feel secondary when they’re released after the more-important CPI data, but considering the December PPI does not incorporate new supply chain issues from conflicts in the Red Sea, this morning’s report feels particularly backward-looking,” said FHN Financial Macro Strategist Will Compernolle.
“As a result, the encouraging aspects of December data on producer prices should be largely dismissed for now,” he added. “We’ll have to wait until January to see how recent supply chain problems pass through to US producer prices.”
Sector News
Airline stocks showed a substantial move to the downside on the day, resulting in a 4.4 percent nosedive by the NYSE Arca Airline Index.
Delta Air Lines (DAL) led the sector lower, plummeting by 9.0 percent despite reporting fourth quarter earnings that exceeded analyst estimates.
Considerable weakness was also visible among housing and banking stocks, with the Philadelphia Housing Sector Index and the KBW Bank Index falling by 1.2 percent and 1.1 percent, respectively.
On the other hand, gold stocks moved sharply higher, driving the NYSE Arca Gold Bugs Index up by 2.8 percent. The strength in the gold sector came amid a surge by the price of the precious metal.
Energy stocks also turned in a strong performance, as the price of crude oil saw further upside after Britain and the U.S. carried out military strikes against targets in Houthi-controlled areas of Yemen
Other Markets
In overseas trading, most stock markets across the Asia-Pacific region moved lower on Friday, although Japan’s Nikkei 225 Index extended its recent rally and jumped by 1.5 percent. Hong Kong’s Hang Seng Index fell by 0.4 percent, while China’s Shanghai Composite Index dipped by 0.2 percent.
Meanwhile, the major European markets moved to the upside on the day. While the U.K.’s FTSE 100 Index climbed by 0.6 percent, the German DAX Index and the French CAC 40 Index jumped by 1.0 percent and 1.1 percent, respectively.
In the bond market, treasuries fluctuated over the course of the session before closing moderately higher. As a result, the yield on the benchmark ten-year note, which moves opposite of its price, fell by 2.7 basis points to 3.950 percent.
Looking Ahead
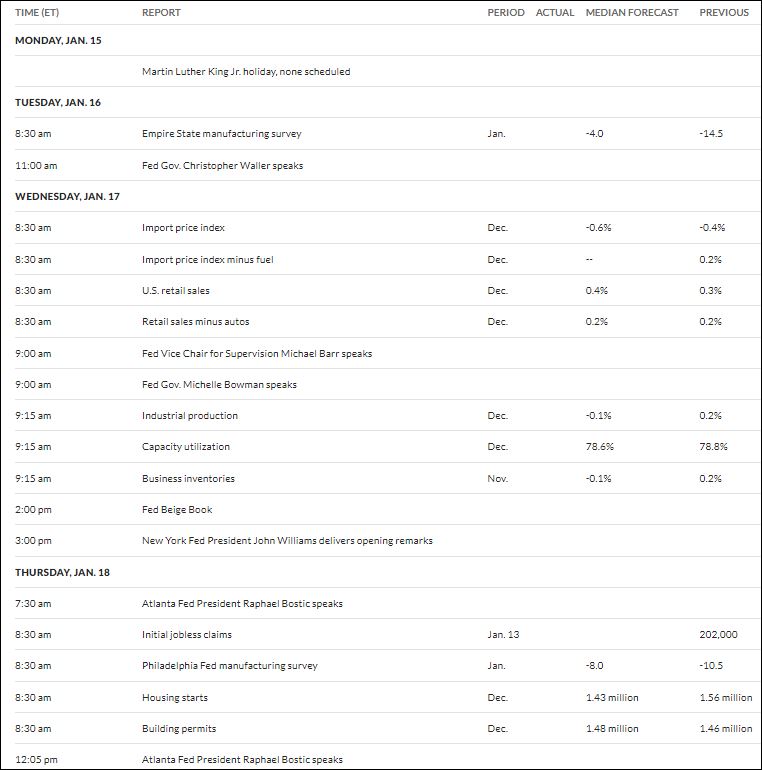
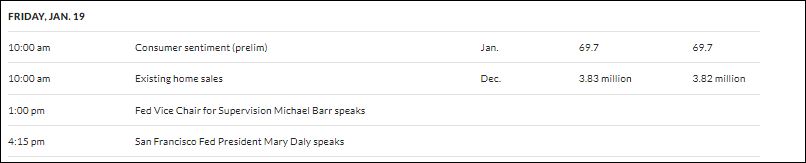
Following the long holiday weekend, next week’s trading may be impacted by reaction to the latest economic news, including reports on retail sales, industrial production, import and export prices, housing starts and consumer sentiment.
Earnings news may also continue to attract attention, with Goldman Sachs (GS), Morgan Stanley (MS), Charles Schwab (SCHW), KeCorp (KEY), M&T Bank (MTB) and Travelers (TRV) among the companies due to report their quarterly results.
https://www.howestreet.com/2024/01/could-2024-be-the-year-of-bitcoin-mark-leibovit/
U.S. DOLLAR
CANADIAN DOLLAR
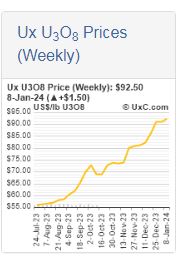
URANIUM – REPORTS ONLY ISSUED WEEKLY
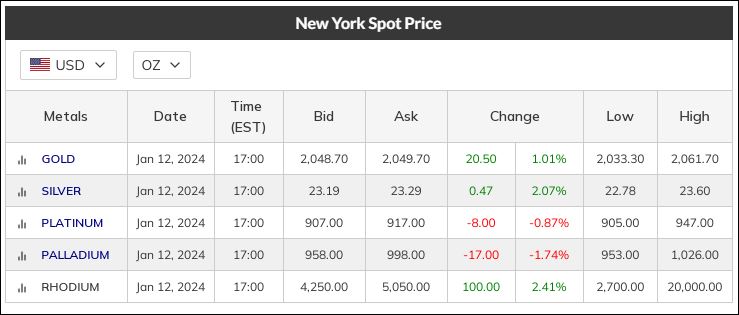
METALS

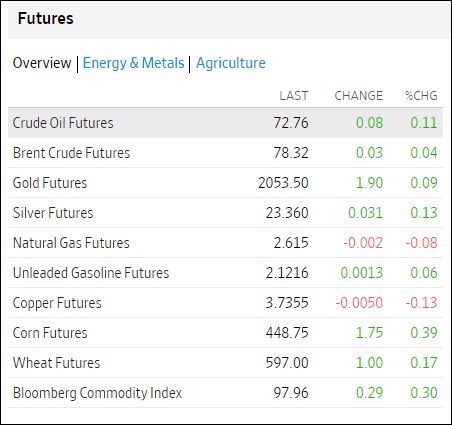
COMMODITIES


https://tinyurl.com/2rd9wv52
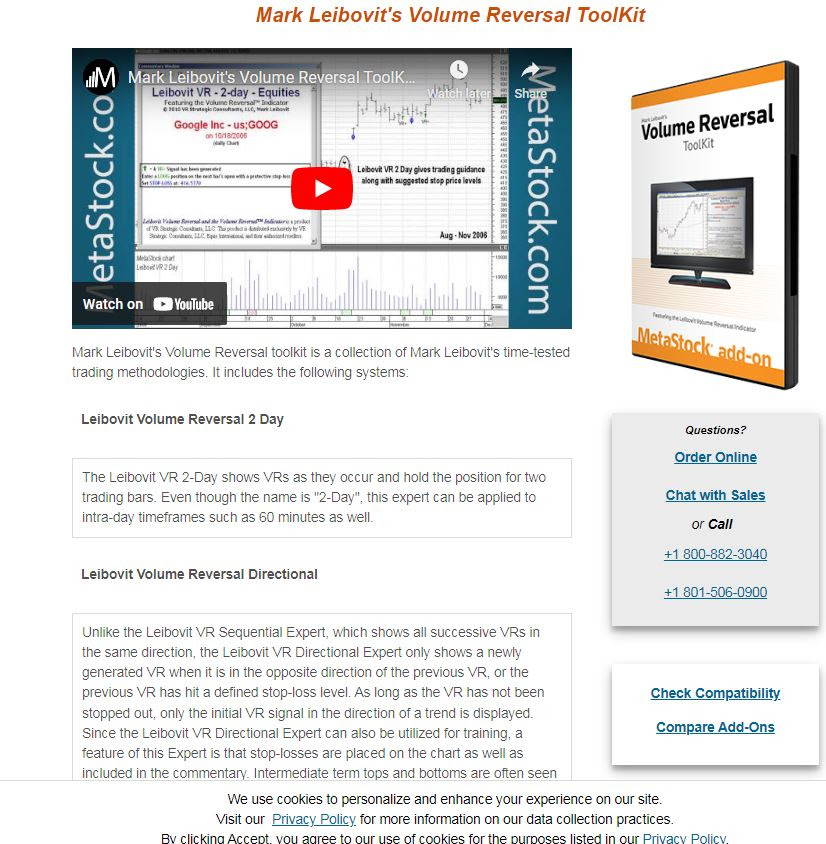
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
https://www.metastock.com/prod

COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.

