
THE VR FORECASTER – ANNUAL FORECAST MODEL WILL BE PUBLISHED BY THE END OF THE FIRST WEEK IN FEBRUARY
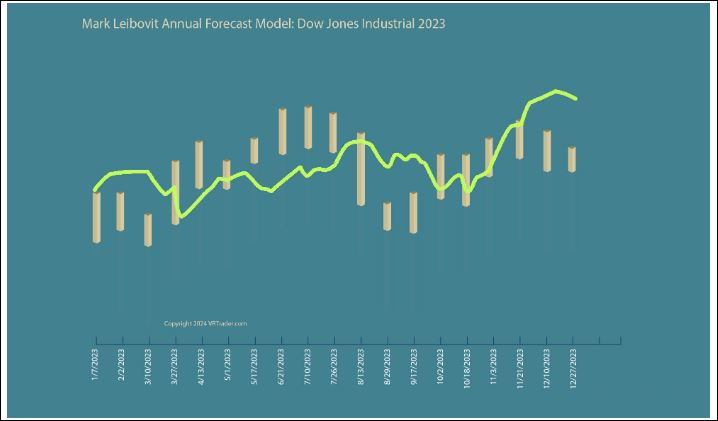
HERE IS THE 2023 ANNUAL FORECAST MODEL WITH THE ‘RESULTS’ SUPERIMPOSED

GENERAL MARKET NEWS
U.S. Close Mixed As Traders Weigh Intel Guidance Against Inflation Data
After trending higher over the past several sessions, stocks turned in a relatively lackluster performance during trading on Friday. The major averages bounced back and forth across the unchanged line before eventually closing narrowly mixed.
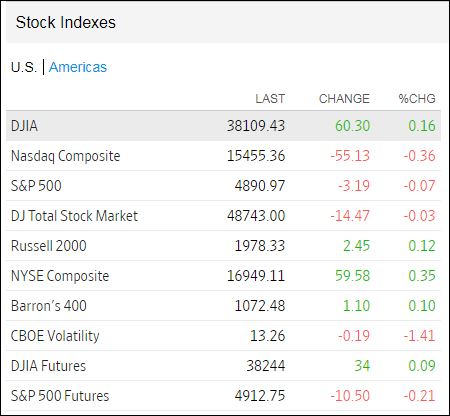
While the S&P 500 edged down 3.19 points or 0.1 percent to 4,890.97 and the Nasdaq fell 55.13 points or 0.4 percent to 15,455.36, the narrower Dow rose 60.30 points or 0.2 percent to a new record closing high of 38,109.43.
Despite the mixed performance on the day, the major averages all moved higher for the week. While the S&P 500 jumped by 1.1 percent, the Nasdaq advanced by 0.9 percent and the Dow climbed by 0.7 percent.
The choppy trading on Wall Street came as traders weighed disappointing earnings news from semiconductor giant Intel (INTC) against tamer than expected consumer price inflation data.
Shares of Intel plunged by 11.9 percent after the company reported better than expected fourth quarter results but provided disappointing first quarter guidance.
Meanwhile, the Commerce Department released a report before the start of trading showing a bigger than expected slowdown in the annual rate of core consumer price growth in the month of December.
The report said the annual rate of growth by core consumer prices, which exclude food and energy prices, slowed to 2.9 percent in December from 3.2 percent in November. Economists had expected core price growth to decelerate to 3.0 percent.
The annual inflation reading, which is said to be preferred by the Federal Reserve, was included in the Commerce Department’s monthly report on personal income and spending.
“Today’s inflation report gives the Fed a path to cut interest rates,” said Larry Tentarelli, Chief Technical Strategist, Blue Chip Daily Trend Report. “Based on strong recent GDP data and jobs data, we expect the first rate cut to be in the May-June period.”
He added, “If jobs and or economic data softens a bit and inflation continues to drop quickly, that could increase the chances of a rate cut in March, but that is not our base case yet.”
Traders may also have been reluctant to make significant moves ahead of the Fed’s monetary policy announcement next week.
While the Fed is widely expected to leave interest rates unchanged, traders will be looking for clues about the timing of highly anticipated rate cuts.
The uptick by the Dow came as shares of American Express (AXP) surged by 7.1 percent after the financial services company reported fourth quarter results that missed estimates but forecast strong results in 2024.
Sector News
Most of the major sectors showed only modest moves on the day, contributing to the lackluster performance by the broader markets.
Semiconductor stocks moved sharply lower amid the steep drop by Intel, however, with the Philadelphia Semiconductor Index plunging by 2.9 percent.
Shares of KLA Corp. (KLAC) also slumped after the semiconductor equipment maker reported better than expected fiscal second quarter results but provided disappointing fiscal third quarter guidance.
Airline stocks also moved to the downside on the day, while some strength was visible among oil producer and steel stocks.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region turned in a mixed performance on Friday. Japan’s Nikkei 225 Index slumped by 1.3 percent, while China’s Shanghai Composite Index inched up by 0.1 percent and South Korea’s Kospi rose by 0.3 percent.
Meanwhile, the major European markets all moved to the upside on the day. While the French CAC 40 Index surged by 2.3 percent, the U.K.’s FTSE 100 Index jumped by 1.4 percent and the German DAX Index climbed by 0.3 percent.
In the bond market, treasuries moved modestly lower after seeing early volatility. Subsequently, the yield on the benchmark ten-year note, which moves opposite of its price, rose 2.8 basis points to 4.160 percent.
Looking Ahead
Next week’s U.S. economic calendar starts off relatively quiet but picks up in the middle of the week with the Fed’s monetary policy announcement on Wednesday.
Later in the week, traders are likely to keep a close eye on the monthly jobs data as well as reports on weekly jobless claims, labor productivity and costs and manufacturing activity.
The latest earnings news may also continue to impact trading, with a slew of big-name companies scheduled to report their quarterly results next week.

February 10:

https://www.howestreet.com/2024/01/china-prohibits-shorting-stocks-mark-leibovit/

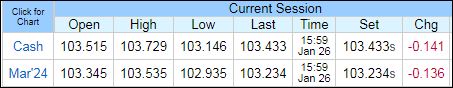
U.S. DOLLAR
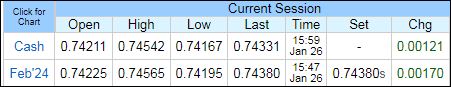
CANADIAN DOLLAR
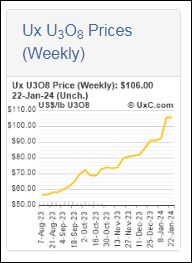
URANIUM – REPORTS ONLY ISSUED WEEKLY
METALS
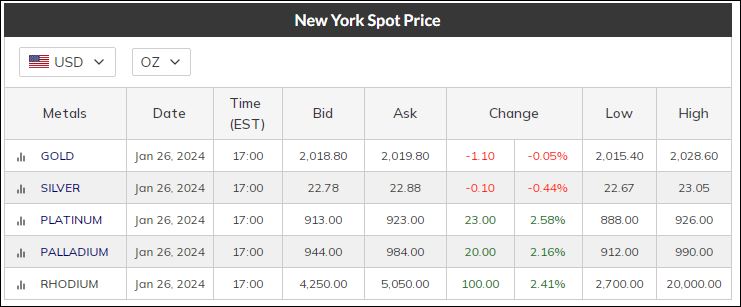

COMMODITIES
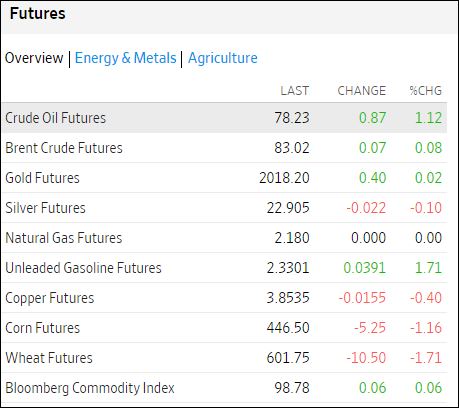



https://tinyurl.com/2rd9wv52
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
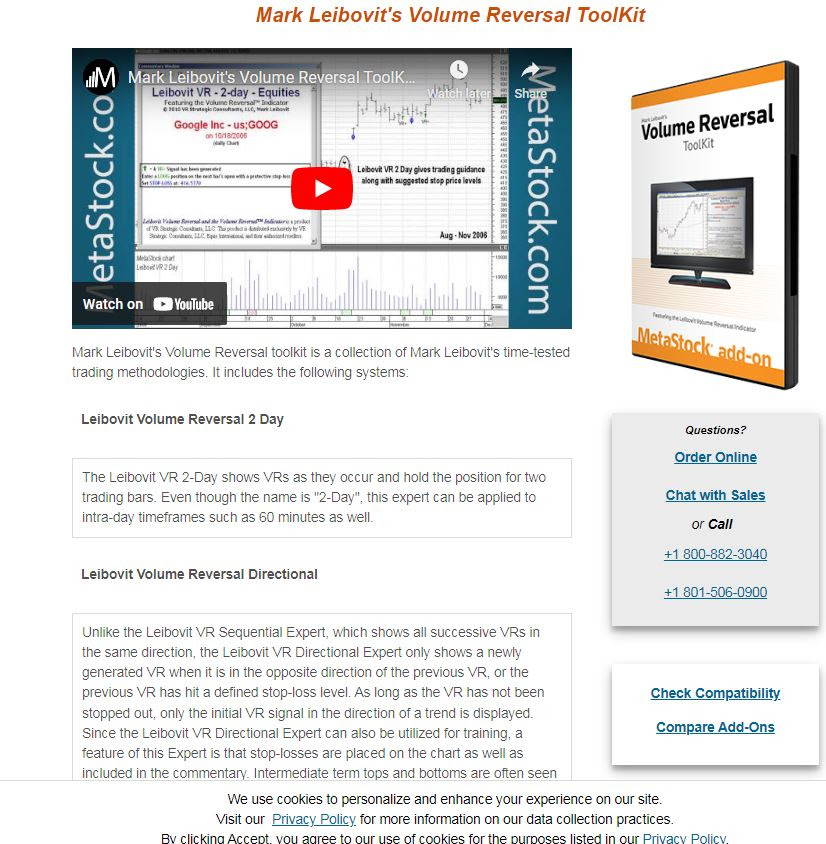
https://www.metastock.com/prod

COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.


[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]