
BOTTOM LINE: TRADE WHAT YOU SEE.
Cycles and breakouts in key indexes say we should short-term remain bullish. The prospects for the market in an election year with a sitting president running for reelection are bullish. At this juncture we expect 2023 to finish strong after a flat first half of December and gains in the 8-12% range for 2024. There could be some ‘first-half’ December tax-loss selling for the losing 2023 stocks.
hen we will be watching for a positive First Five Days and the month-end January Barometer.
What used to be known as the “January Effect” of small-cap out performance can last from mid-December through March. Small caps, notably the Russell 2000 Index has been lagging and remains under water since its November 2021 high.
Investors are bullish because they widely expect stocks to rally once the Fed cuts interest rates. However, contrary to popular opinion, when the Fed cuts rates that’s typically when the heaviest selling of stocks begins! This will be interesting to watch.
And Wall Street will make sure to continue to spread the bullish “recovery,” “no recession in sight,” and “inflation is coming down” narrative, regardless of what the true facts show.
Markets are being manipulated higher and we can enjoy the ride while we can, but CAUTION IS ADVISED. The picture may look different come January and my work says we could see the beginnings of a sell-off into the first quarter. As always, we will ‘know in the fullness of time’.
Fortunately, we have picked quite a few of winning stocks and indexes, including precious metals, uranium, bitcoin and even oil on the recent rally.
The Dow and the S&P 500 reached their best closing levels since early 2022, while the tech-heavy Nasdaq ended the day at a four-month closing high.
While the Dow jumped 294.61 points or 0.8 percent to 36,245.50, closing high for the fourth straight session, the S&P 500 advanced 26.83 points or 0.6 percent to 4,594.63 and the Nasdaq climbed 78.81 points or 0.6 percent to 14,305.03.
For the week, the Dow surged by 2.4 percent, the S&P 500 increased by 0.8 percent and the Nasdaq rose by 0.4 percent.
The strength on Wall Street partly reflected ongoing optimism about the outlook for interest rates following the release of a report from the Institute for Supply Management showing a continued contraction in U.S. manufacturing activity in the month of November.
The ISM said its manufacturing PMI came in at 46.7 in November, unchanged from October, with a reading below 50 indicating a contraction. Economists had expected the index to inch up to 47.6.
“The weaker-than-expected ISM survey will reinforce financial markets’ expectations that the Fed’s next move is a cut,” said Bill Adams, Chief Economist for Comerica Bank.
Stocks saw further upside even after Federal Reserve Chair Jerome Powell’s called speculation about interest rate cuts “premature” during remarks at Spelman College.
Powell acknowledged recent signs of slowing price growth but said the Fed is committed to keeping monetary policy restrictive until officials are confident inflation is on a path to 2 percent.
“It would be premature to conclude with confidence that we have achieved a sufficiently restrictive stance, or to speculate on when policy might ease,” Powell said.
Powell stressed the Fed is prepared to tighten policy further if it becomes appropriate, although most economists believe the central bank is done raising rates.
Jeffrey Roach, Chief Economist for LPL Financial, suggested traders viewed Powell’s comments as inching toward the dovish camp.
“A few weeks ago, Powell said policy is restrictive but today, he believes policy is ‘well into restrictive territory,'” Roach said. “I think it’s fair for markets to latch on to that subtlety.”
Transportation stocks extended the strong upward move seen on Thursday, driving the Dow Jones Transportation Average up by 3.0 percent to a three-month closing high.
Substantial strength also emerged among networking stocks, as reflected by the 2.8 percent surge by the NYSE Arca Networking Index. The index reached its best closing level in two months.
Banking stocks also saw significant strength on the day, with the KBW Bank Index jumping by 2.7 percent to a nearly four-month closing high.
Tobacco, telecom, housing and commercial real estate stocks also moved notably higher amid broad based buying interest on Wall Street.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region moved mostly lower during trading on Friday. Japan’s Nikkei 225 Index slipped by 0.2 percent, while Hong Kong’s Hang Seng Index dove by 1.3 percent.
Meanwhile, the major European markets moved to the upside on the day. While the French CAC 40 Index climbed by 0.5 percent, the U.K.’s FTSE 100 Index and the German DAX Index jumped by 1.0 percent and 1.1 percent, respectively.
In the bond market, treasuries showed a substantial rebound following the pullback seen on Thursday. As a result, the yield on the benchmark ten-year note, which moves opposite of its price, tumbled 12.6 basis points to a three-month closing low of 4.352 percent.
Looking Ahead
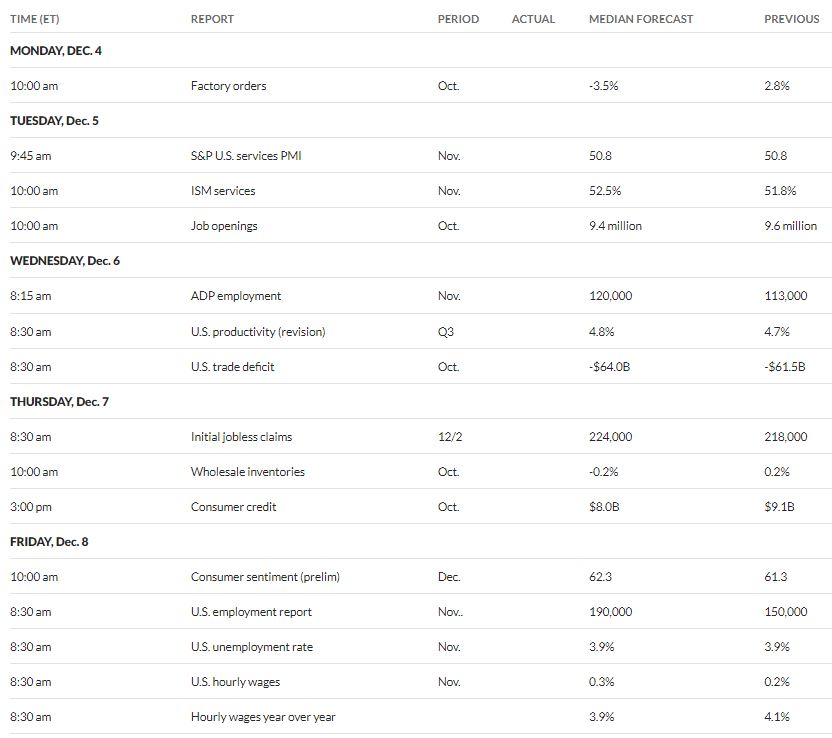
The Labor Department’s closely watched monthly jobs report is likely to move into the spotlight next week, while traders are also likely to keep an eye on reports on service sector activity, job openings and consumer sentiment.
November 30 interview
https://www.howestreet.com/2023/11/gold-showing-new-life-mark-leibovit/
CRYPTO UPDATE AS OF DECEMBER 2, 2023




https://tinyurl.com/2rd9wv52
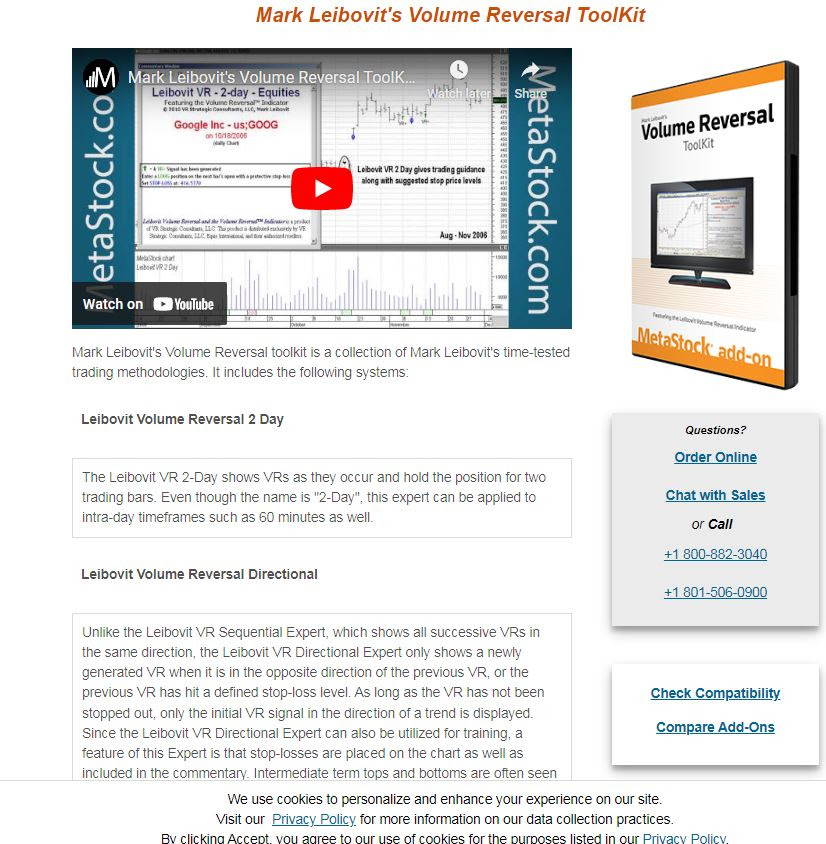
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
https://www.metastock.com/

COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.


[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]