

U.S. MARKETS: GENERAL PRESS COMMENTARY
After ending Wednesday’s volatile session narrowly mixed, stocks moved mostly higher during trading on Thursday. The major averages all moved to the upside on the day, with the tech-heavy Nasdaq leading the advance.
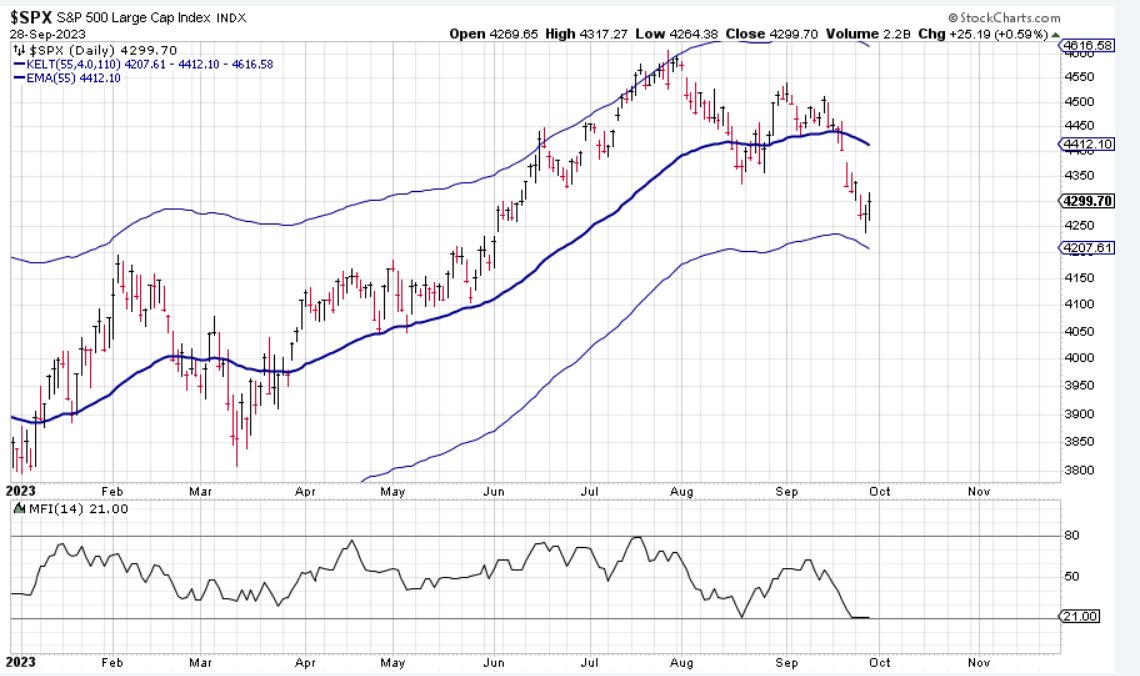
While the Nasdaq climbed 108.42 points or 0.8 percent to 13,201.28, the S&P 500 increased 25.19 points or 0.6 percent to 4,299.70 and the Dow rose 116.07 points or 0.4 percent to 33,666.34.
The strength on Wall Street partly reflected bargain hunting, as traders picked up stocks at reduced levels following recent weakness.
Concerns about the outlook for interest rates have weighed on the markets in recent session, dragging the major averages down to their lowest levels in three months.
A downturn by treasury yields also contributed to the strength among stocks, with the yield on the benchmark ten-year note giving back ground after reaching its highest levels since October 2007.
Meanwhile, traders were also looking ahead to remarks by Federal Reserve Chair Jerome Powell, which kicked off just as the markets close.
Powell is hosting a town hall with educators in Washington, D.C. and nationwide via webcast, with the Fed chief set to respond to questions from the in-person audience and virtual participants from across the country.
On the economic front, the Commerce Department released a report this morning showing the pace of U.S. economic growth in the second quarter of 2023 was unrevised from the previous estimate.
The Commerce Department said real gross domestic product increased by 2.1 percent in the second quarter, unrevised from the estimate provided last month. The unrevised reading matched economist estimates.
The unrevised GDP growth in the second quarter still reflects a slight slowdown compared to the 2.2 percent growth in the first quarter.
A separate report released by the Labor Department showed a slight increase in first-time claims for U.S. unemployment benefits in the week ended September 23rd.
The Labor Department said initial jobless claims crept up to 204,000, an increase of 2,000 from the previous week’s revised level of 202,000.
Economists had expected jobless claims to rise to 215,000 from the 201,000 originally reported for the previous week.
Sector News
Semiconductor stocks showed a strong move to the upside on the day, driving the Philadelphia Semiconductor Index up by 1.8 percent. The index climbed further off their four-month closing low set on Tuesday.
Considerable strength was also visible among computer hardware stocks, as reflected by the 1.7 percent gain being posted by the NYSE Arca Computer Hardware Index.
Networking, housing and brokerage stocks also saw notable strength, while interest rate-sensitive utilities stocks saw further downside.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region turned in a mixed performance on Thursday. Japan’s Nikkei 225 Index and Hong Kong’s Hang Seng Index tumbled by 1.5 percent and 1.4 percent, respectively, while China’s Shanghai Composite Index and South Korea’s Kospi both inched up by 0.1 percent.
Meanwhile, the major European markets all moved to the upside on the day. While the U.K.’s FTSE 100 Index crept up by 0.1 percent, the French CAC 40 Index climbed by 0.6 percent and the German DAX Index advanced by 0.7 percent.
In the bond market, treasuries showed a significant turnaround after coming under pressure in early trading. Subsequently, the yield on the benchmark ten-year note, which moves opposite of its price, fell 2.9 basis points to 4.597 percent.
Looking Ahead
Reaction to Powell’s remarks are likely to impact trading on Friday along with a report on personal income and spending that includes readings on inflation said to be preferred by the Fed.
END OF THE MONTH ‘WINDOW DRESSING’ BOUNCE TIED TO GEOCOSMIC CYCLES AND OVERSOLD TECHNICAL INDICATORS
Mark Leibovit: How to Protect Investments With Unpredictable US Government – Sept. 28, 2023
https://tinyurl.com/muynvd3v
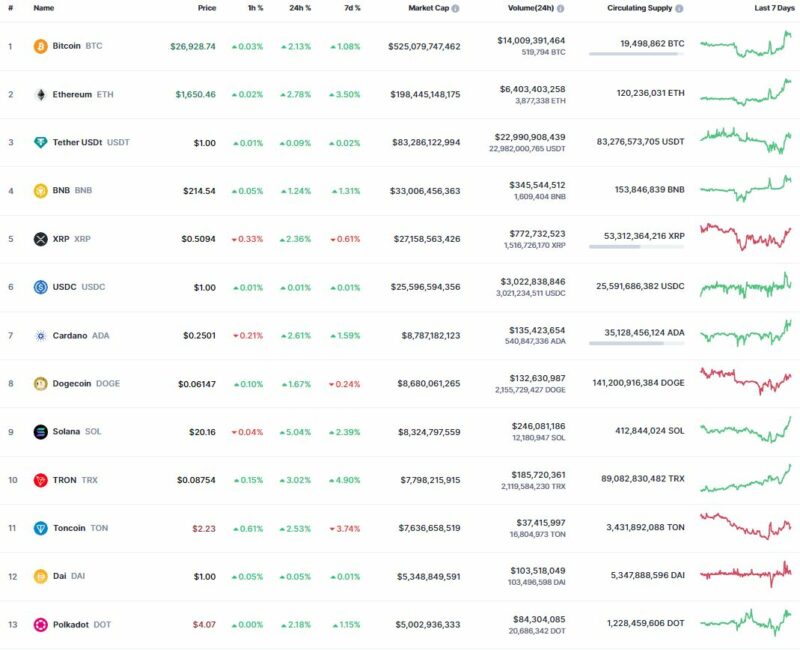
CRYPTO UPDATE AS OF SEPTEMBER 28:
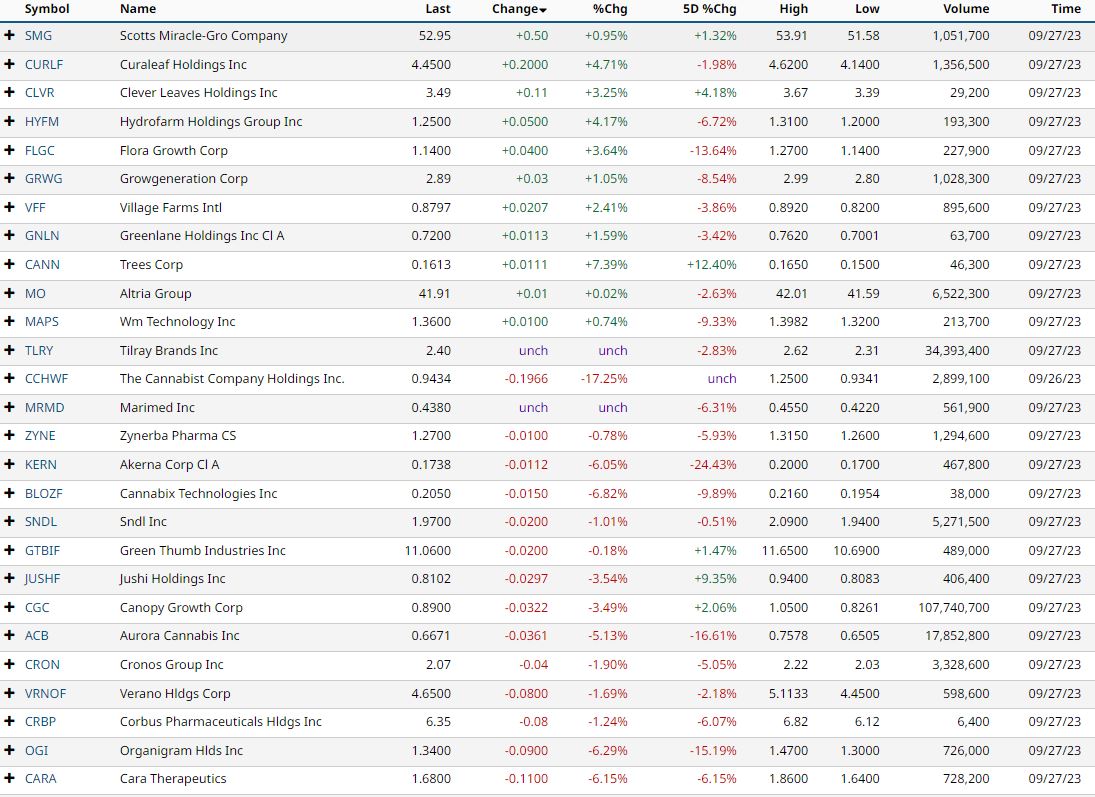
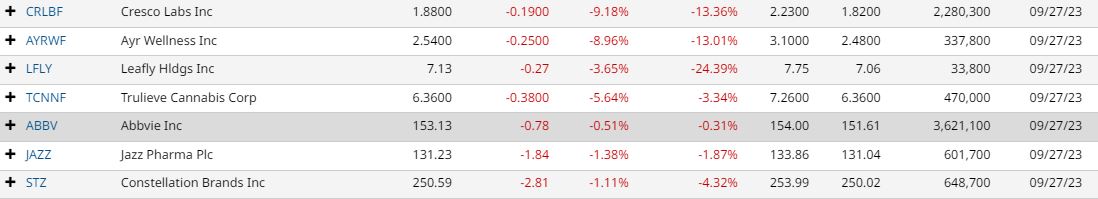
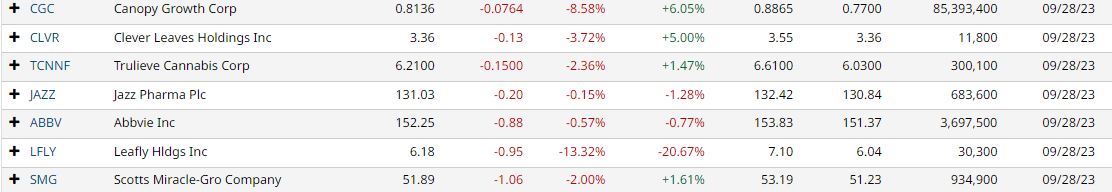
CANNABIS MOVERS AND SHAKERS SEPTEMBER 27:


Toward the Brink -Daily Reckoning
by James Rickards
Should market participants be concerned about the possible government shutdown at midnight on Sept. 30?
It’s too soon to answer that question definitively, but it’s not too soon for investors to take some defensive action.
If it does happen, it’ll be different from those that have gone before. Let’s break it all down…
While most of us keep our books and records on a Dec. 31 fiscal year, the U.S. government is different. The U.S. fiscal year runs from Oct. 1 until midnight on Sept. 30.
The fiscal year is dated by the calendar year in which the last day falls.
So the fiscal year beginning on Oct. 1, 2023, is called “Fiscal Year 2024” by the Government Accounting Office (GAO) and the Office of Management and Budget (OMB). Leave it to the government to make things difficult and hard to follow, but that’s how they do it.
That means fiscal year 2023 ends at midnight on Sept. 30, 2023. We’re up against the clock and that’s why you’re hearing so much about a government shutdown right now.
It’s the job of Congress to pass appropriations bills to keep the government open. Under so-called regular order, each major department has its own appropriations bill. So there should be separate bills for Defense, the State Department, the Department of Education and so on.
Each bill should be voted on separately and each bill should pass before Sept. 30 to keep that department and the government as a whole running in the new fiscal year.
But in the real world, the “regular order” process never happens. Typically, the House and Senate and the two parties in each body can’t agree on anything by Sept. 30
JPMorgan CEO Jamie Dimon Says This Is the Number One Risk Threatening Global Economy – And It’s Not Inflation – The Daily Hodl
Jamie Dimon is comparing the current American market sentiment to a sugar high and is concerned many are unprepared for what is on the horizon. He advises investors to batten down the hatches and prepare for some hardship ahead.
by Henry Kanapi
JPMorgan chief executive Jamie Dimon says that the global economy is facing a far greater risk than persistent inflation or high interest rates.
In a new interview on CNBC India, Dimon says that people should prepare for higher oil and gas prices as well as higher interest rates.
While Dimon is urging people and businesses to be ready for higher energy costs along with tight monetary policies, he highlights that his number one concern is the current geopolitical situation.
According to Dimon, the war in Ukraine is negatively impacting oil, gas and food prices. He also notes that it is “affecting all global relationships.”
“I think the geopolitical situation is the thing that most concerns me, and we don’t know the effect of that on the economy. Again, I think the humanitarian part – that’s far more important.
I think it’s very important for the future of the free democratic world. We may be at an inflection point for the free democratic world. That’s how seriously I take it…
We have dealt with inflation before, we have dealt with deficits before [and] we have dealt with recessions before. We haven’t really seen something like this pretty much since World War II … There is no playbook.”
The SEC is Snooping on All Your Trades
EDITOR’S NOTE: The War on Cash is fought on a variety of fronts but the end result is always a loss of liberty and privacy for us all. The SEC’s sharing of the data on every market move we make is just the latest strategy. While the tracking should be alarming in and of itself, the threat of this information being open to hacking is of even greater concern. A centralized database to track every American investor is, without question, an unconstitutional data grab; but can it be stopped?
What’s in Your Portfolio? The SEC is Snooping on All Your Trades -MishTalk.com
portfolioThe SEC is now tracking your stock trades by your Social Security Number. It shares the data with 3,000 outside agencies.
In 2012 the SEC approved a new rule requiring a Consolidated Audit Trail to Monitor and Analyze Trading Activity.
“A consolidated audit trail that accurately tracks orders throughout their lifecycle and identifies the broker-dealers handling them will provide us with an unprecedented ability to effectively oversee the markets we regulate,” said SEC Chairman Mary Schapiro.
The new rule becomes effective 60 days after its publication in the Federal Register. SROs are required to submit the NMS plan to the Commission within 270 days of the rule’s publication in the Federal Register. Once the Commission approves the NMS plan, the SROs are required to report the required data to the central repository within one year, and members of the SROs are required to report within two years. Certain small broker-dealers will have up to three years to report the data.
This ruling was in response to a 2010 flash crash and quietly sat for years. The SEC is now following through.
The scope of the Consolidated Audit Trail, or CAT, a regulation the SEC issued in 2016 but implemented only recently, is breathtaking and unprecedented. In the words of the SEC press release, the regulation instructs regulated financial institutions to identify “every order, cancellation, modification and trade execution for all exchange-listed equities and options across all U.S. markets.”
‘Bond King’ Jeffrey Gundlach warns of ‘demons on the horizon’ for stocks – and predicts a dollar disaster and recession next year -Yahoo! Finance

by Theron Mohamed
Jeffrey Gundlach issued a slew of warnings about the stock market, the US dollar, and an upcoming recession during the Future Proof conference last week.
The S&P 500 and Nasdaq Composite have surged 16% and 31% respectively this year, as investors price in the potential boost to companies from artificial intelligence and future cuts to interest rates. However, they’re overlooking “demons on the horizon,” Gundlach cautioned.
The billionaire CEO of DoubleLine Capital highlighted signs of a faltering US economy as a key concern. He pointed to a recent wave of corporate layoffs, and consumers feeling the squeeze from record amounts of credit-card debt as red flags. He also noted the chilling effect of higher mortgage rates on the housing market, and the challenge for small businesses of having to refinance their debts at much higher interest rates.
“The economy is definitely weakening,” Gundlach said. “I look for one next year, and I think the indicators are getting really convincing in that regard,” he said about the prospect of a recession.
The fund manager — whose nickname is the “Bond King” — also argued that economic growth has been shored up this year by a dangerous and unsustainable amount of government spending.
“The economy is only growing because we have a budget deficit that is 8% of GDP,” he said. “It’s about the same today as the depths of the global financial crisis.”
Gundlach underscored that the federal government financed most of its spending at rock-bottom rates. However, the Federal Reserve’s war on inflation has seen it hike rates from nearly zero to over 5% since last spring, meaning the government’s interest charges on trillions of dollars of debt are poised to balloon.

https://tinyurl.com/2rd9wv52
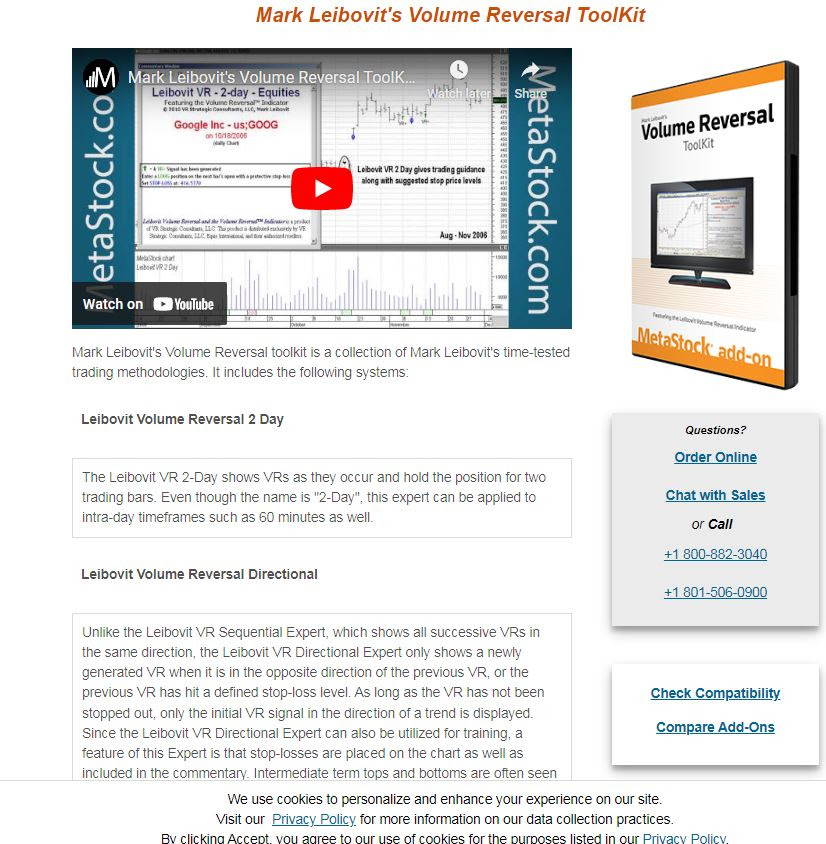
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
https://www.metastock.com/
COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.