
FOR THOSE WHO ARE INTERESTED IN BARRETT-JACKSON CAR AUCTIONS – THE BIG ONE IS GOING ON NOW IN SCOTTSDALE, AZ: HERE IS THE LINK
https://www.barrett-jackson.com/Live/Streaming/Video/b3d7796a-599e-49c9-b10f-2235e5c8deac/BLOCK


Why am I showing the stock market during World War II? Well, we’ve entered World War III (different type of war, maybe), but sometimes patterns rhyme. Looks like the ‘power that be’ knew about the Japanese attack well in advance as the market declined into December 7. Meanwhile, the Governor of Texas has defied the lawless, unconstitutional SCOTUS order that demands Texas open its border and allow an unlimited invasion of enemy combatants into the country. Gov. Abbott has invoked the U.S. Constitution to declare that the rights of Texas supersede the federal government’s powers. Democrats are calling for Biden to seize control of the Texas National Guard. But Oklahoma, Virginia, Florida and other states have declared they will stand with Texas. We are rapidly advancing into a civil war scenario over illegal immigration.

U.S. Stocks Close Mostly Higher Amid Positive Reaction To Economic Data
Stocks gave back ground after an early advance but rebounded going into the close to end Thursday’s trading mostly higher. The Dow and the S&P 500 once again reached new record closing highs, while the Nasdaq edged up its best closing level in well over two years.
The Dow ended the session just off its best levels of the day, climbing 242.74 points or 0.6 percent to 38,049.13. The S&P also rose 25.61 points or 0.5 percent to 4,894.16, while the tech-heavy Nasdaq crept up 28.58 points 0.2 percent to 15,510.50.
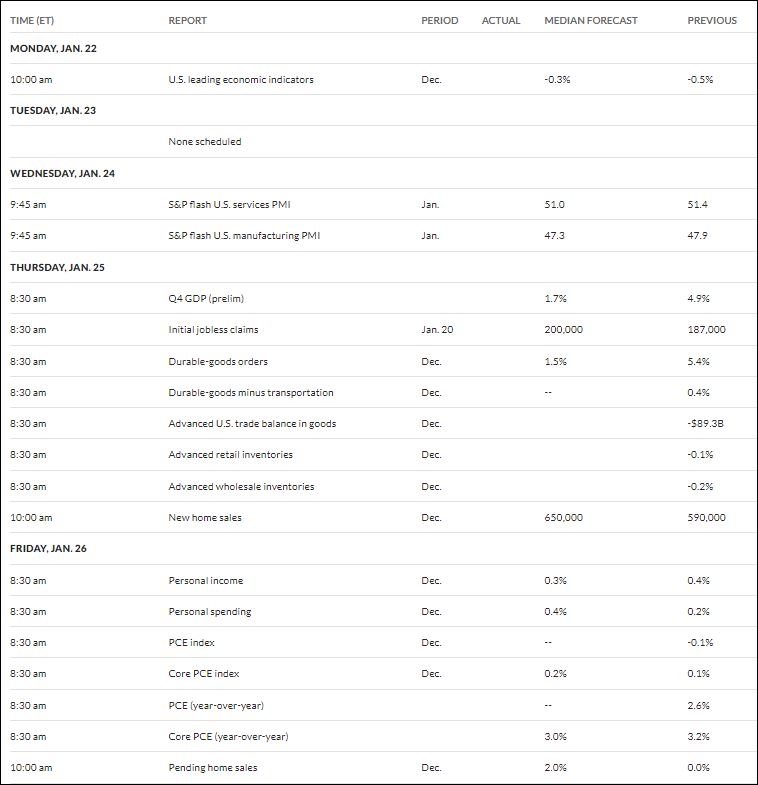
The early strength on Wall Street came following the release of a Commerce Department report showing stronger than expected U.S. economic growth as well as a slowdown in the pace of consumer price growth in the fourth quarter of 2023.
The report said gross domestic product shot up by 3.3 percent in the fourth quarter after surging by 4.9 percent in the third quarter, while economists had expected GDP to jump by 2.0 percent.
The stronger than expected GDP growth partly reflected a continued surge in consumer spending, which shot up by 2.8 percent in the fourth quarter after spiking by 3.1 percent in the third quarter.
On the inflation front, the Commerce Department said the personal consumption expenditures price index increased 1.7 percent in the fourth quarter compared with a 2.6 percent jump in the third quarter.
Excluding food and energy prices, the PCE price index increased 2.0 percent in the fourth quarter, the same as in the third quarter.
“The headline data are the perfect mix of strong consumption and dropping inflation,” said Jamie Cox, Managing Partner for Harris Financial Group. “This is exactly what you want to see if you are running the Fed and want to move rates lower this year.”
Meanwhile, the Commerce Department also released a report showing new orders for U.S. manufactured durable goods unexpectedly came in unchanged in the month of December.
The report said durable goods orders were virtually unchanged in December after surging by an upwardly revised 5.5 percent in November.
Economists had expected durable goods orders to jump by 1.1 percent compared to the 5.4 percent spike that had been reported for the previous month.
Excluding orders for transportation equipment, durable goods orders increased by 0.6 percent in December after climbing by 0.5 percent in November. Ex-transportation orders were expected to inch up by 0.2 percent.
A separate report released by the Labor Department showed first-time claims for U.S. unemployment benefits rebounded by more than expected in the week ended January 20th.
The Labor Department said initial jobless claims climbed to 214,000, an increase of 25,000 from the previous week’s revised level of 189,000.
Economists had expected initial jobless claims to rise to 200,000 from the 187,000 originally reported for the previous week.
Buying interest waned over the course of the session, however, as traders looked ahead to the release of a closely watched report on personal income and spending on Friday.
The personal income and spending report includes readings on inflation said to be preferred by the Federal Reserve and could have a significant impact on the outlook for interest.
Among individual stocks, tech giant IBM Corp. (IBM) posted a standout gain, soaring by 9.5 percent after reporting fourth quarter results that exceeded analyst estimates on both the top and bottom lines.
Sector News
Airline stocks moved sharply higher over the course of the session, with the NYSE Arca Airline Index soaring by 3.4 percent.
A substantial increase by the price of crude oil also contributed to significant strength among oil stocks, as reflected by the 2.3 percent gain jump by the NYSE Arca Oil Index.
Telecom stocks also saw considerable strength after falling sharply on Wednesday, driving the NYSE Arca North American Telecom Index up by 1.8 percent.
Interest-rate sensitive housing and utilities also moved notably higher, while strength was also visible among gold, natural gas and commercial real estate stocks.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region moved mostly higher during trading on Thursday. Japan’s Nikkei 225 Index closed just above the unchanged line, while Hong Kong’s Hang Seng Index jumped by 2.0 percent and China’s Shanghai Composite Index surged by 3.0 percent.
The major European markets also showed modest moves to the upside after the ECB left interest rates unchanged. While the U.K.’s FTSE 100 Index closed marginally higher, the German DAX Index and the French CAC 40 Index both inched up by 0.1 percent.
In the bond market, treasuries climbed firmly into positive territory in reaction to the U.S. economic data. As a result, the yield on the benchmark ten-year note, which moves opposite of its price, slid 4.6 basis points to 4.132 percent.
Looking Ahead
The readings on consumer price inflation contained in the Commerce Department’s personal income and spending report are likely to be in the spotlight on Friday.
Nonetheless, trading may also be impacted by reaction to earnings news from Intel (INTC), with the semiconductor giant due to report its fourth quarter results after the close of today’s trading.

FOMC MEETINGS 2024
JAN 31
MARCH 20
MAY 1
JUNE 12
JULY 31
SEPT 18
NOV 7
DEC 1
https://www.howestreet.com/2024/01/china-prohibits-shorting-stocks-mark-leibovit/


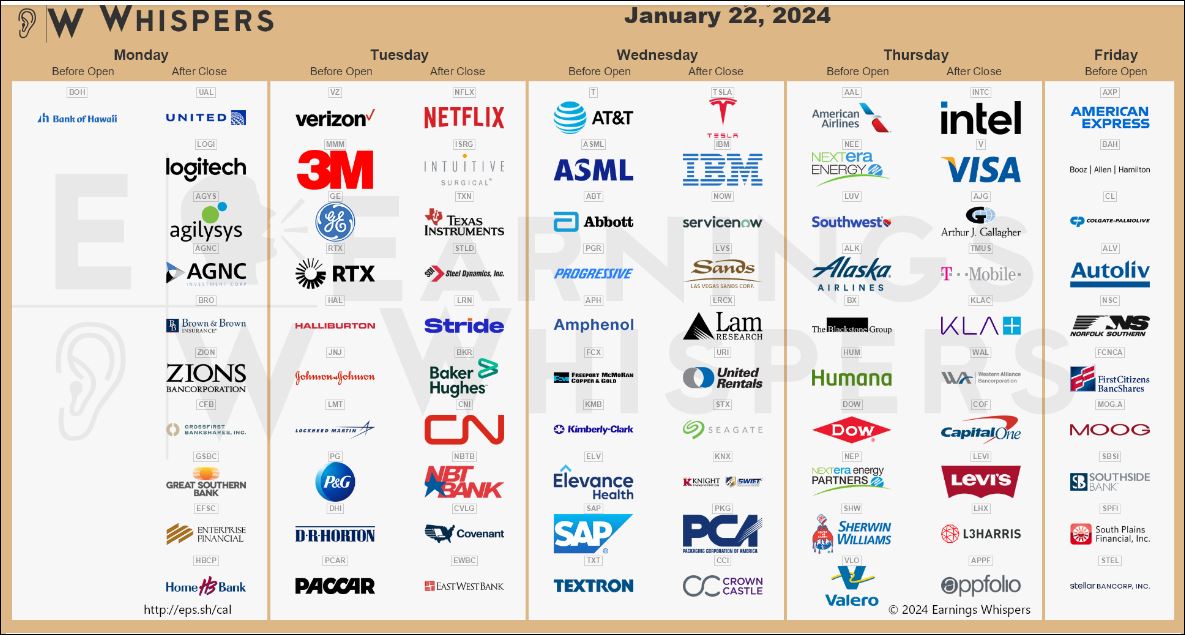


https://tinyurl.com/2rd9wv52
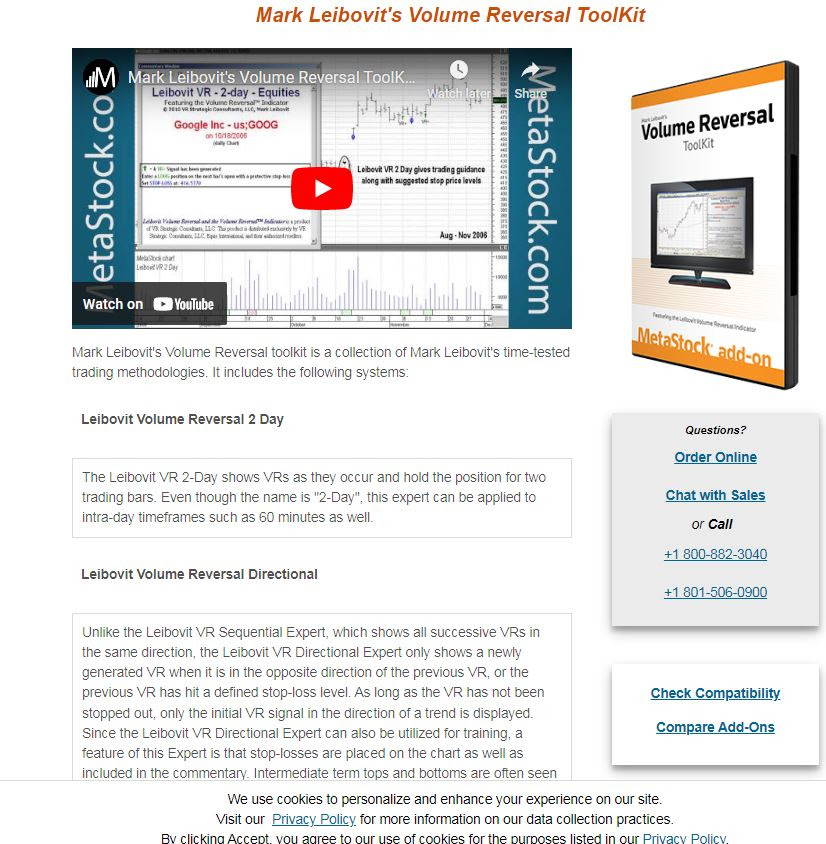
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
https://www.metastock.com/prod

COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.


[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]