
https://talkdigitalnetwork.substack.com/p/mark-leibovit-can-government-manipulation
NEXT PODCAST THURSDAY EVENING
https://schwabnetwork.com/video/the-big-3-xrp-gold-spcx?utm_source=chatgpt.com
https://tinyurl.com/bdfcfwyw
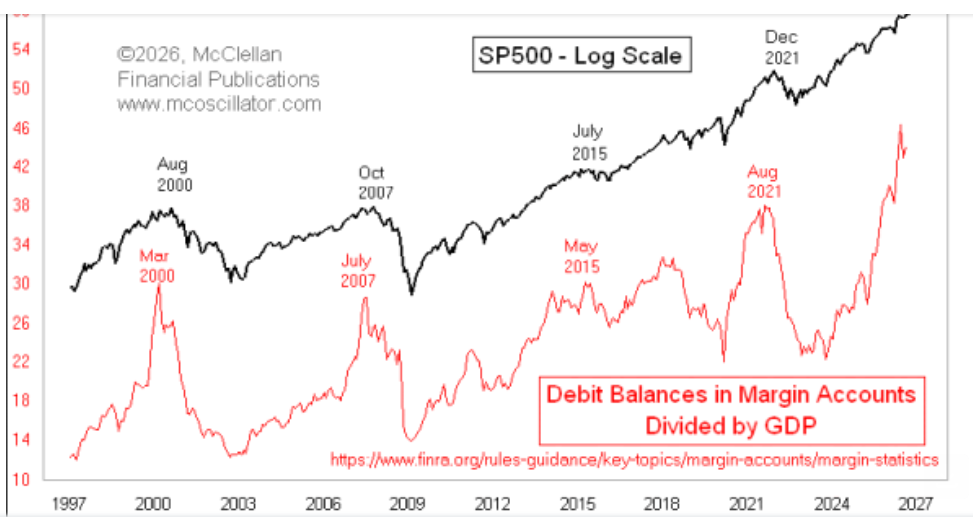
This is about the toughest market I’ve seen in numerous years. I see many people taking positions that look good and reverse the opposite direction out of nowhere.
Until the main indexes are all going the same direction, this market will be tough.
Last night I said Newsom is closing refineries. What really happened is he changed rules and things the refineries are subject to and two companies are each closing one refinery, representing about 15 to 20 percent of the refining capacity in California.
If Trump shores up the USA rare earth companies, USA semiconductor companies, I’ve got to side with Trump shoring up the refining capacity of the oil we drill here and to eliminate dependance on the oil that foreign countries have that we need for what our refineries can refine.
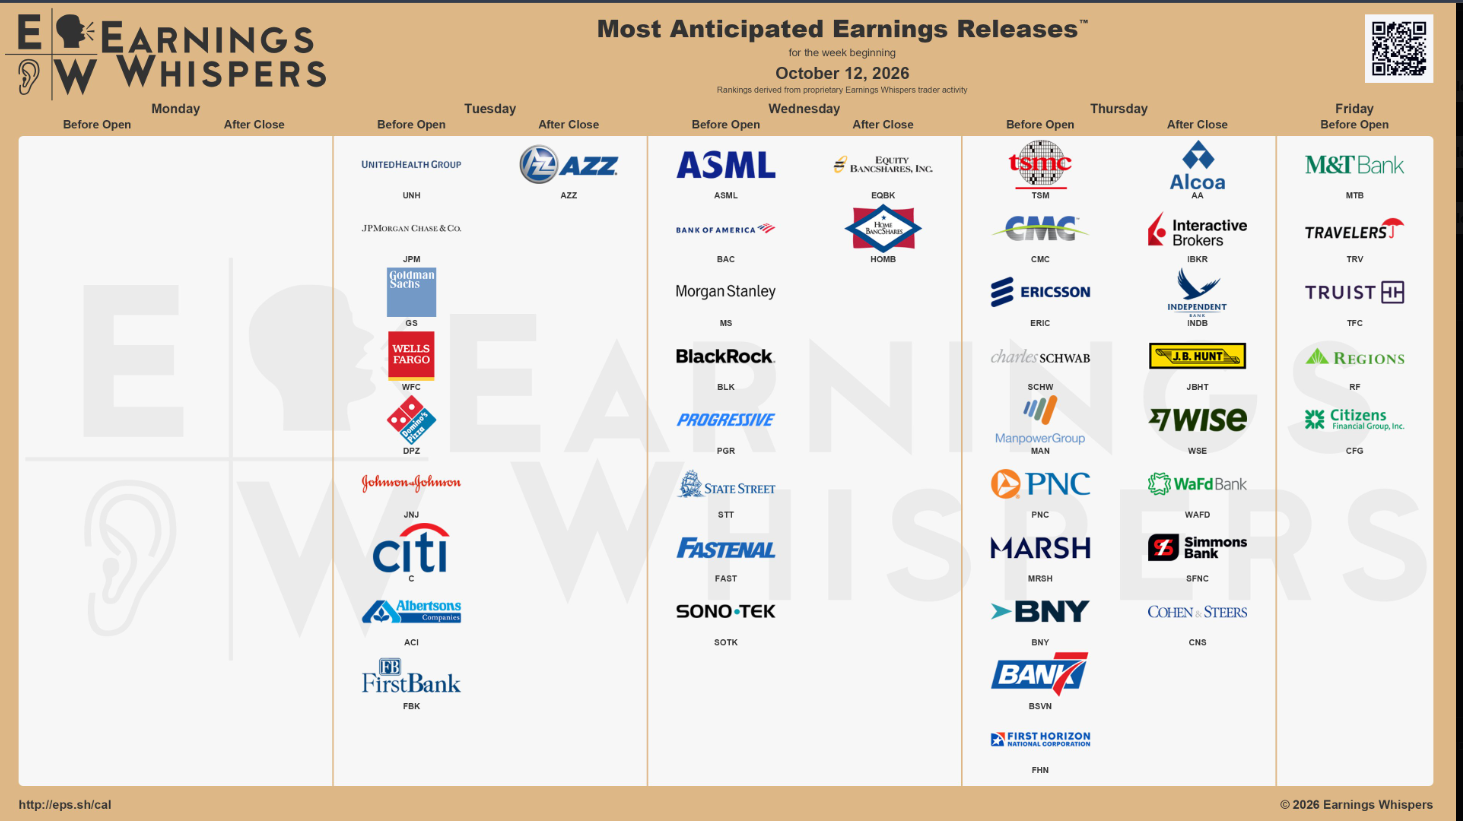
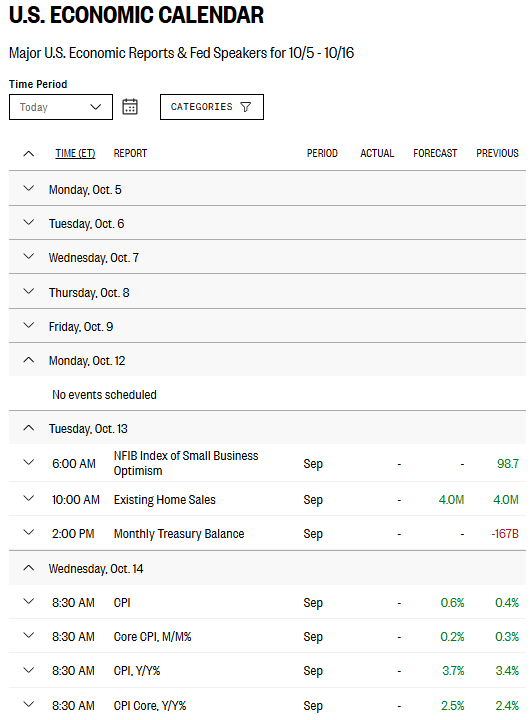
Tomorrow morning is CPI. When the CPI is released, the CPI-W will be announced and that will determine the amount of COLA increase that people on Social Security will get. This amount is based on the average of July, August and September data. The increase for social security in 2027 is expected to be around 3.4% to 3.6% Naturally, the higher the increase, the Social Security Trust fund will run short sooner. You have to love the threat when the congressmen are doing zero to resolve it.
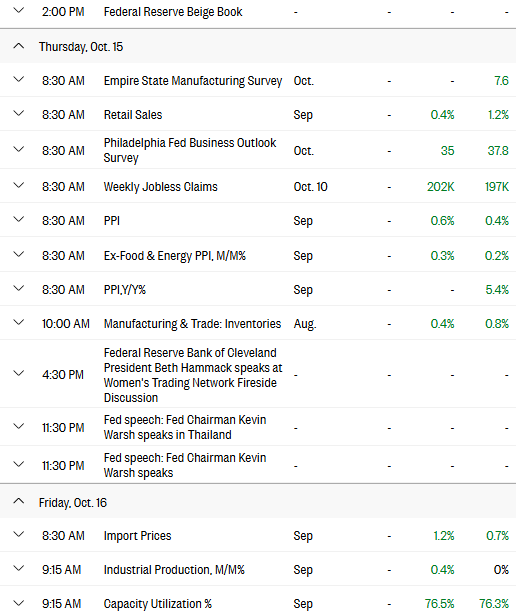
Thursday is PPI.
Options epiration is Friday.
There is nothing positive at the present time saying the market should rally. The last two weeks of October are “typically” not positive. We will have to see. After October, the trend is possibly up into year end. The only question is how broad the advance will be.
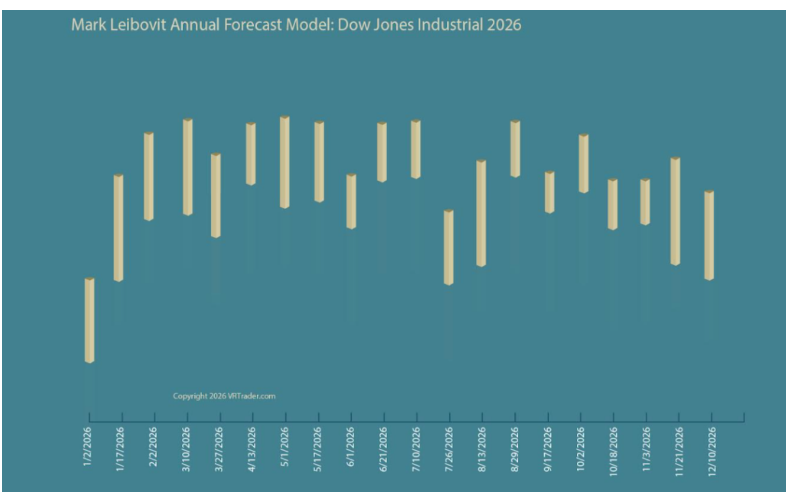
Judy Shelton and Gold: Her Vision for a Gold-Backed Dollar
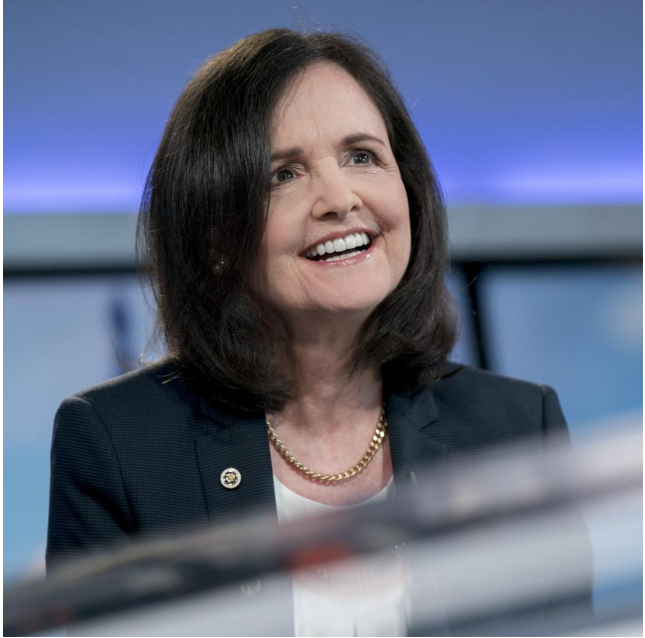
Judy Shelton is an American monetary economist, former Federal Reserve Board nominee, and prominent advocate of restoring a formal connection between the U.S. dollar and gold.
Her central argument is that gold can serve as an anchor for monetary stability, limiting the government’s ability to expand the money supply without discipline.
What Shelton proposes
Shelton’s ideas go beyond simply encouraging investors to own gold.
-
Gold-linked Treasury bonds: Issue government securities that promise repayment linked to a specified quantity of gold.
-
Sound money: Reestablish a monetary system that protects the dollar’s purchasing power over long periods.
-
Monetary discipline: Reduce dependence on discretionary Federal Reserve policy.
-
International monetary reform: Explore using gold as a neutral reference point for exchange rates and international settlements.
Her proposals do not necessarily mean immediately returning to the classical gold standard, under which dollars could be exchanged for gold at a legally fixed price.
Breaking development: October 9, 2026
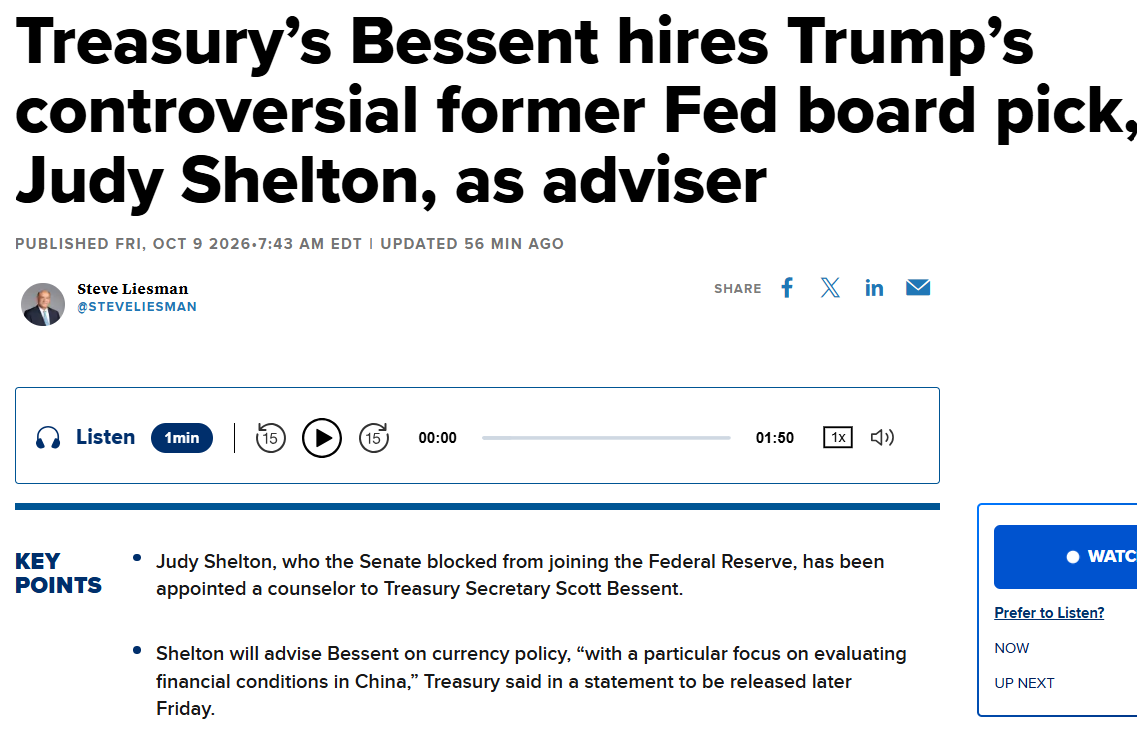
Shelton has just been appointed an adviser to Treasury Secretary Scott Bessent.
Her responsibilities reportedly include currency policy and evaluating financial conditions in China. This places a prominent gold advocate closer to U.S. monetary policymaking, although it does not establish that the administration will adopt her gold proposals.
What could this mean for gold prices?
Potential gold-price scenarios
| Gold-linked Treasury bonds announced | Potentially bullish for gold sentiment |
| Formal gold revaluation | Impact depends on the new valuation and monetary rules |
| Stronger dollar credibility | Could reduce some safe-haven demand |
| No policy implementation | Gold remains driven largely by yields, dollar, inflation and central-bank demand |
For perspective, the United States holds approximately 261.5 million troy ounces of official gold reserves.
| Gold price | Approximate reserve value |
|---|---|
| $4,000 | $1.05 trillion |
| $5,000 | $1.31 trillion |
| $7,500 | $1.96 trillion |
| $10,000 | $2.61 trillion |
These are valuation scenarios, not Shelton’s price targets. The official accounting value remains approximately $42.22 per ounce.
Her book and interviews
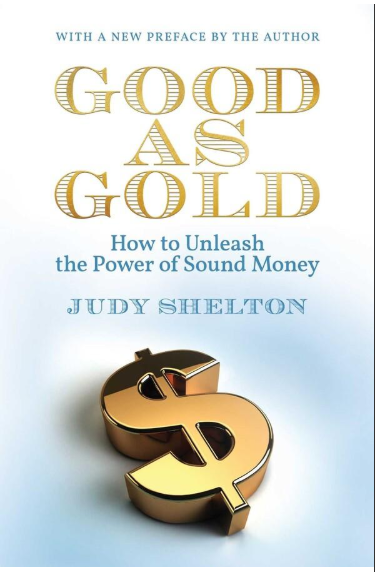
Good as Gold: How to Unleash the Power of Sound Money
Published in 2024, the book develops her case for gold-linked monetary reform and Treasury Trust Bonds.
Also see her Kitco interview on gold and Federal Reserve reform.
The important question now: Will Shelton’s appointment lead to actual gold-backed Treasury securities, or will her influence remain advisory?
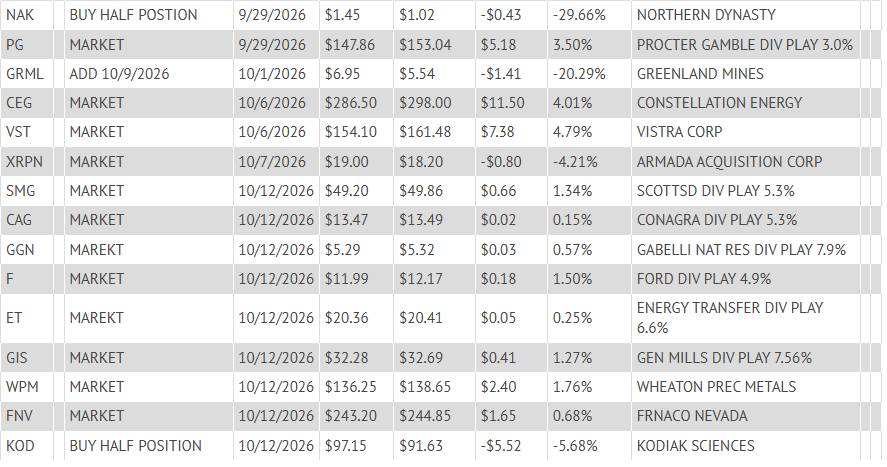
CURRENT HYPOTHETICAL PORTFOLIO MODEL:
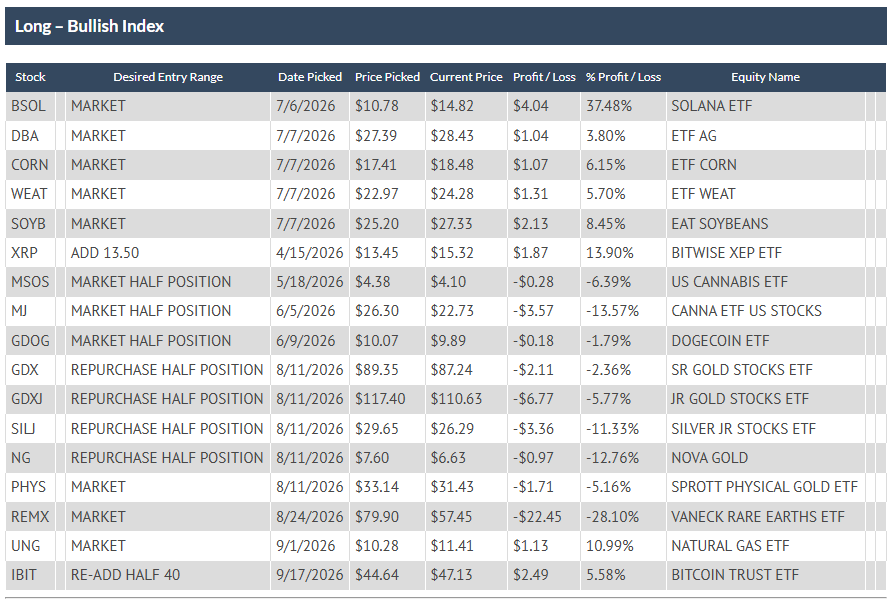
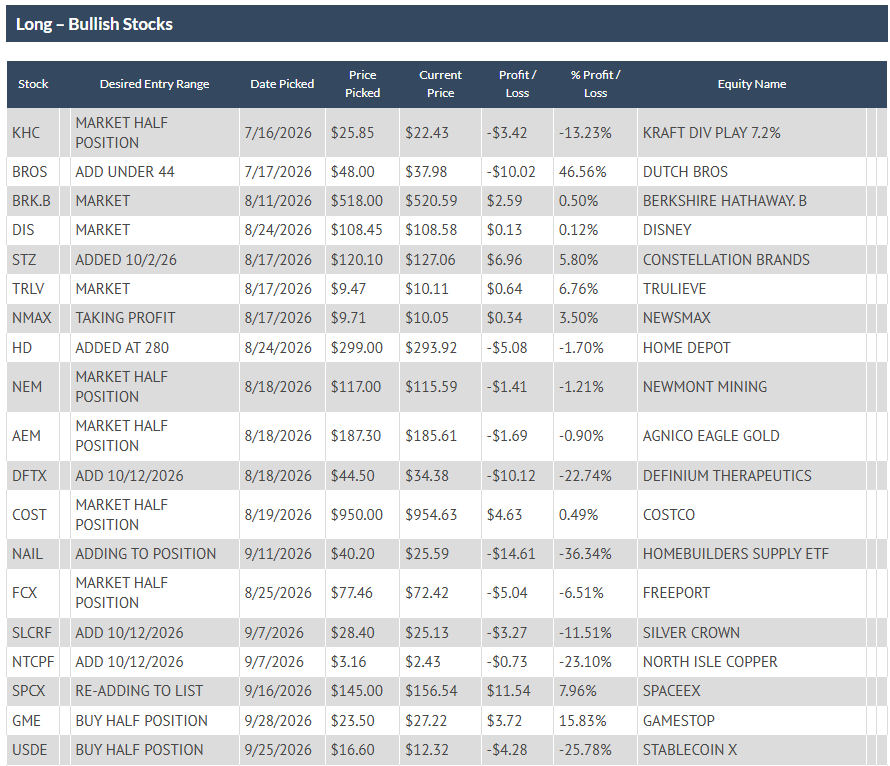
CRYPTO
OCTOBER 14, 2026 UPDATE BELOW BUT USE THE LINK FOR A MORE CURRENT UPDATE
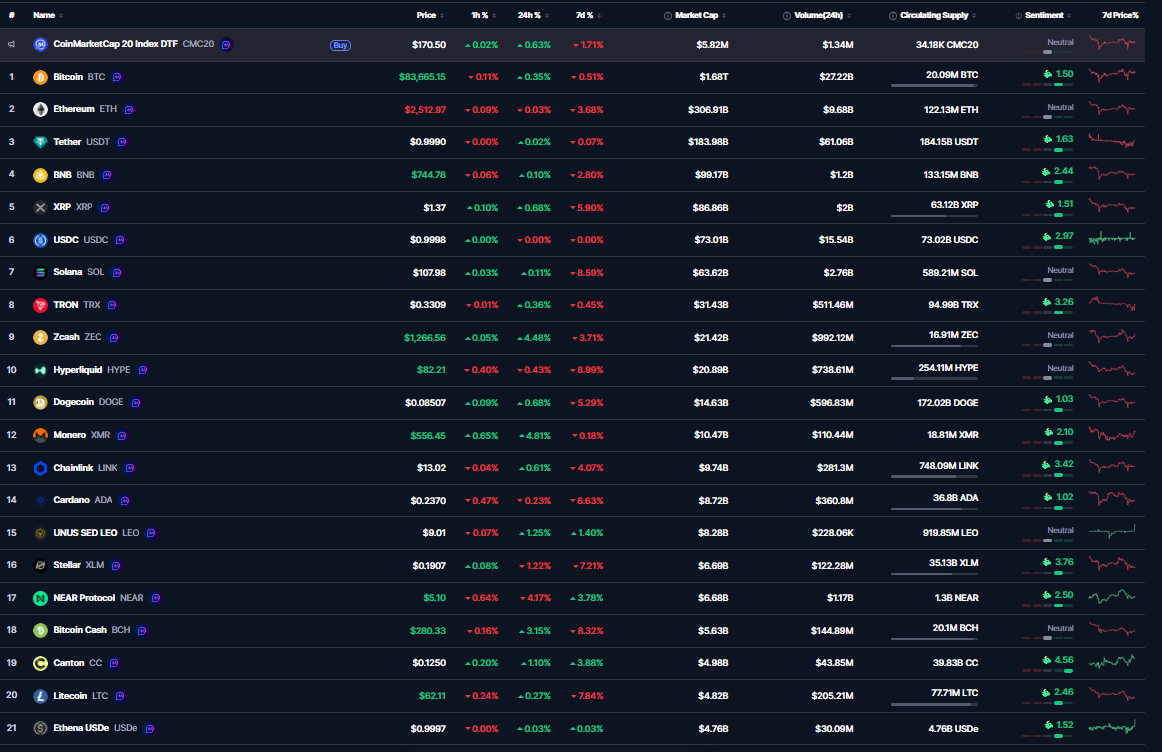
https://coinmarketcap.com/
SIGN UP FOR THE VR BLOCKCHAIN LETTER:



ORDER LINK:
https://tinyurl.com/3tjv5up6\
I AM AVAILABLE FOR TECHNICAL CONSULTATION ON THE VOLUME REVERSAL (TM) STRATEGY AND ACCOMPANYING TECHNICAL ANALYSIS. PLEASE EMAIL MARK.VRTRADER@GMAIL.COM
One interesting piece of Wall Street Week history is that my profile places me among a relatively small group of market technicians who achieved long-term national visibility through the show,Wall Street Week with Louis Rukeyser.
Seven years as a Wall Street Week Elf
More than thirty years as a Market Monitor guest on PBS’s Nightly Business Report
Two-time Timer Digest #1 market-timing recognition twice
Creator of the trademarked Volume Reversal Indicator.
END THE FED:
We as citizens and voters indeed have a lot to do. We need to overhaul or abolish the FED. After 113 years of incompetence and stupidity, including rates during the Great Depression, we have take the bull by the horns and get our Congress to reverse the decision made in 1913. I have with help prepared an initial document which should be entered as legislation in Congress:
RESTORE CONGRESSIONAL MONETARY AUTHORITY ACT OF 2026
Congress created the Federal Reserve in 1913. Congress has the authority to restructure or replace the statutory system it created.
This proposal draws in part on monetary-reform ideas previously advanced by Congressman Ron Paul and G. Edward Griffin—but addresses a critical question:
If the Federal Reserve is abolished or fundamentally restructured, what replaces it without destabilizing America or the global financial system?
The proposal would:
• Restore congressional authority over the nation’s monetary framework.
• End the Federal Open Market Committee’s independent monetary-policy authority—but ONLY after a replacement monetary system is operational.
• Prevent simply transferring unlimited money-creation power from the Fed to the Treasury.
• Require Congress to consider a rules-based dollar, gold/precious-metals linkage, commodity backing, Treasury-issued money under strict limits, and other alternatives.
• Preserve the U.S. dollar and existing lawful contracts.
• Protect bank deposits and deposit insurance.
• Honor Treasury securities and prohibit repudiation of U.S. debt.
• Keep Fedwire, ACH, FedNow, currency distribution and essential settlement systems operating without interruption.
• Determine who provides emergency liquidity during a genuine banking crisis—and place strict statutory limits on that authority.
• Transfer banking supervision to appropriate regulators.
• Require a comprehensive accounting of Federal Reserve assets, liabilities, securities, guarantees and commitments.
• Address the international consequences of restructuring the institution behind the world’s principal reserve currency.
• Establish contingency plans for disruption in Treasury, banking, credit, foreign-exchange and dollar-funding markets.
• Require a STAGED transition. There would be no overnight shutdown and no monetary vacuum.
The objective isn’t simply “End the Fed.”
The larger question is:
What monetary system should replace the Federal Reserve—and how do we prevent the successor from acquiring the same unlimited monetary powers under another name?
That is the debate Congress should have.
PROPOSAL TO RESTRUCTURE COMEX GOLD AND SILVER MARKETS
RESTORE HONEST PRICE DISCOVERY
PURPOSE
The purpose of this proposal is to strengthen confidence in the U.S. gold and silver futures markets by ensuring that futures-market price discovery remains reasonably connected to the supply, demand, ownership and availability of physical precious metals.
Futures markets perform legitimate and important functions, including hedging, liquidity and risk transfer. The concern is that excessive leverage, concentrated positions and an enormous volume of financial contracts relative to immediately deliverable physical metal can create conditions in which derivatives trading exerts disproportionate influence over gold and silver prices.
The solution is not necessarily to abolish futures trading. The solution is greater transparency, accountability, physical-market discipline and independent verification.
PROPOSED REFORMS
1. Establish a meaningful physical-backing standard
COMEX should establish reasonable limits between outstanding futures exposure and the quantity of registered metal demonstrably available for delivery. The market should not permit unlimited expansion of paper exposure without regard to underlying deliverable supply.
2. Strengthen delivery requirements
Contracts representing physical commodities should retain a credible connection to physical delivery. Exchange rules should ensure that participants standing for legitimate delivery cannot be disadvantaged by a market structure overwhelmingly dependent upon offsetting, rolling or financial settlement.
3. Publish a Paper-to-Physical Exposure Ratio
The exchange should prominently disclose, in plain English:
-
Total gold and silver futures open interest;
-
Equivalent ounces represented by those contracts;
-
Registered inventories available for delivery;
-
Eligible inventories held in approved warehouses;
-
Actual deliveries;
-
Warehouse inflows and withdrawals; and
-
The resulting relationship between paper exposure and immediately deliverable physical metal.
Registered and eligible inventories should be clearly distinguished.
4. Strengthen position limits and aggregation rules
The CFTC and exchange should review whether existing position limits adequately prevent excessive concentration.
Positions controlled by affiliated or related entities should be aggregated where appropriate so that position limits cannot effectively be circumvented through multiple accounts, subsidiaries or related financial instruments.
Hedge exemptions should be transparent and subject to meaningful regulatory review.
5. Require independent third-party audits
COMEX-approved depositories should undergo regular independent physical audits.
Public reporting should include sufficient information to verify inventories, including bar lists, serial numbers where practicable, registered-versus-eligible classifications, audit methodology and appropriate assay verification.
Investors should not be expected simply to take inventory claims on faith.
6. Increase transparency of concentrated positions
Regulators should provide greater disclosure regarding unusually concentrated long and short positions while protecting legitimate confidential trading information.
The public should be able to determine whether a handful of institutions have acquired sufficient derivatives exposure to exert disproportionate influence over price discovery.
7. Strengthen anti-manipulation surveillance
The CFTC and exchange should aggressively monitor:
-
Spoofing;
-
Layering;
-
Coordinated trading;
-
Sudden exceptionally large orders;
-
Concentrated short selling;
-
Trading designed primarily to trigger stop-loss orders; and
-
Other practices capable of producing artificial price movements.
Enforcement should be timely enough to deter misconduct rather than merely penalize it years later.
8. Reduce excessive leverage
Margin requirements should reflect the size, volatility and physical liquidity of the underlying precious-metals market.
Extremely large speculative positions should require sufficient capital so that enormous leveraged derivatives positions cannot cheaply overwhelm normal physical-market price signals.
9. Incorporate physical-market conditions into surveillance
Persistent physical premiums, backwardation, shortages, extraordinary delivery demand or unusual warehouse withdrawals should automatically trigger enhanced regulatory review.
A futures benchmark should not become disconnected for extended periods from the commodity it is supposed to price.
10. Restore confidence in gold and silver price discovery
COMEX can remain an important international marketplace only if producers, industrial users, investors and the public believe its prices result from a transparent and competitive market.
The objective is simple:
ONE MARKET — TRANSPARENT RULES — VERIFIABLE METAL — HONEST PRICE DISCOVERY
Congress and the Commodity Futures Trading Commission should undertake a comprehensive review of the structure of U.S. precious-metals futures trading and determine whether current leverage, position limits, exemptions, warehouse reporting and delivery mechanisms adequately protect the integrity of gold and silver price discovery.
If the present system cannot demonstrate a reasonable relationship between derivatives trading and the underlying physical market, structural reform is warranted.
DANNY SHEEHAN AND SUMMARY OF JOE ROGAN INTERVIVEW
https://tinyurl.com/4xed3m4m
I HOPE YOU ARE SITTING DOWN FOR THIS ONE. THE MISSION TO MARS THAT HAS BEEN COVERED UP FOR DECADES. I HAD HEARD ABOUT THIS 40 YEARS AGO, SO NO SURPRISE TO ME! SPACEX AND ELON MUSK ARE SIMPLY TAKING OVER RESEARCH AND EXPLORATION THAT HAVE ALREADY OCCURRED. I KNOW IT’S HARD TO BELIEVE, BUT NOT TO THOSE WHO UNDERSTAND GOVDERNMENT COVERUPS!
https://tinyurl.com/2ves55wa

MY 2027 BOOK IN THE WORKS:


DISCLAIMER
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2026. All rights reserved.

[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]