
Joy to the World, the Fed Is Here It’s the most wonderful time of the year.
The Christmas miracle of the Federal Reserve’s dovish pivot pushed the yield on the 10-year Treasury below four percent on Thursday, 10 basis points lower than where they ended after yesterday’s sharp decline. The two-year yield fell by about 12 basis points to 4.365, the lowest since the start of June.
Wall Street was also busy decking the halls with blue chip stocks. The Dow Jones Industrial Average rose to a fresh record high as traders decked the halls, even as the
Nasdaq slipped a bit.
The market moves reflect the fact that Jerome Powell and his colleagues at the Fed were more dovish than expected.
GENERAL NEWS:
U.S. Stocks See Further Upside Following Dovish Fed Pivot
Following the substantial rally seen late in the previous session, stocks saw further upside during trading on Thursday. Buying interest was somewhat subdued on the day, although the Dow still managed to reach a new record closing high.
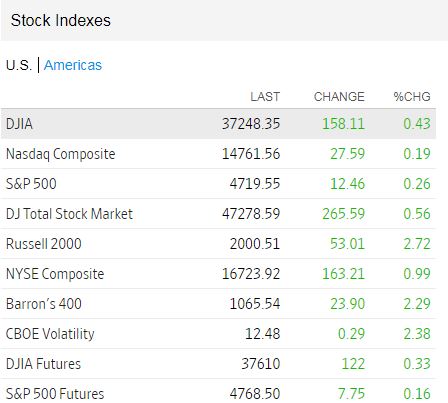
The Dow climbed 158.11 points or 0.4 percent to 37,248.35, closing higher for the sixth consecutive session. The Nasdaq edged up 27.59 points or 0.2 percent to 14,761.56 and the S&P 500 rose 12.46 points or 0.3 percent to 4,719.55, reaching their best closing levels in almost two years.
Stocks continued to benefit from a positive reaction to the Federal Reserve’s monetary policy announcement on Wednesday.
The Fed left interest rates unchanged, as widely expected, and signaled plans to cut interest rates three times next year.
Since the Fed’s projections are often more conservative, traders are expecting the central bank to slash rates even further than forecast in 2024.
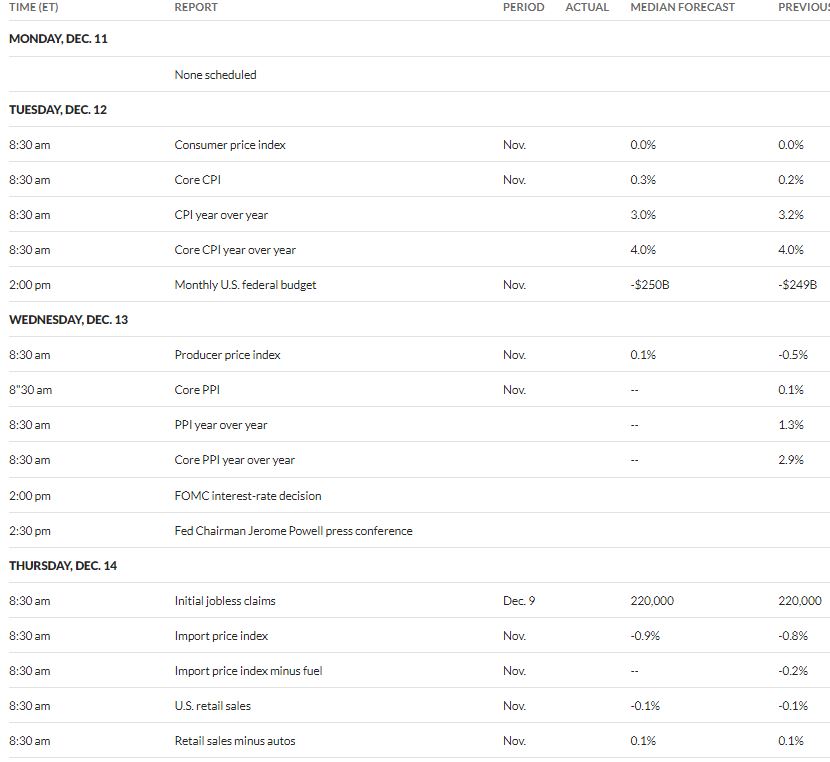
Adding to optimism the economy is headed toward a soft landing, the Commerce Department released a report this morning showing an unexpected increase in U.S. retail sales in November.
The Commerce Department said retail sales rose by 0.3 percent in November after slipping by a downwardly revised 0.2 percent.
Economists had expected retail sales to edge down by 0.1 percent, matching the dip originally reported for the previous month.
Excluding sales by motor vehicle and parts dealers, retail sales inched up by 0.2 percent in November after coming in unchanged in October. Ex-auto sales were expected to slip by 0.1 percent.
Meanwhile, the Labor Department released a separate report showing first-time claims for U.S. unemployment benefits unexpectedly decreased in the week ended December 9th.
The report said initial jobless claims fell to 202,000, a decrease of 19,000 from the previous week’s revised level of 221,000.
Economists had expected jobless claims to come in unchanged compared to the 220,000 originally reported for the previous week.
Housing stocks turned in some of the market’s best performances on the day, driving the Philadelphia Housing Sector Index up by 5.8 percent to a record closing high.
Substantial strength was also visible among banking stocks, as reflected by the 5.1 percent spike by the KBW Bank Index. The index reached its best closing level in over nine months.
Oil service stocks also moved sharply higher along with the price of crude oil, with the Philadelphia Oil Service Index surging by 4.4 percent.
Brokerage, commercial real estate and semiconductor stocks also saw significant strength, while software and utilities stocks showed notable moves to the downside.
Other Markets
In overseas trading, stock markets across the Asia-Pacific region turned in a mixed performance during trading on Thursday. Japan’s Nikkei 225 Index shed 0.7 percent, while Hong Kong’s Hang Seng Index jumped by 1.1 percent.
Meanwhile, European stocks moved mostly higher on the day. The U.K.’s FTSE 100 Index surged by 1.3 percent and the French CAC 40 Index climbed by 0.6 percent, although the German DAX Index bucked the uptrend and edged down by 0.1 percent.
In the bond market, treasuries extended the substantial rally seen in the previous session. As a result, the yield on the benchmark ten-year note, which moves opposite of its price, tumbled by 10.3 basis points to a new four-month closing low of 3.930 percent.
Looking Ahead
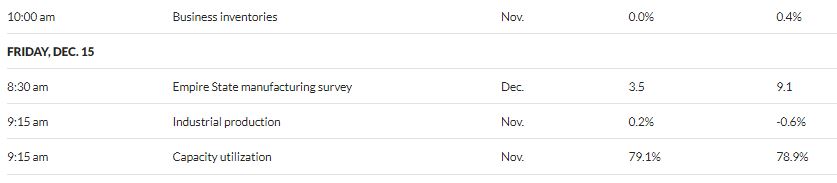
Trading on Friday may be impacted by reaction to the Federal Reserve’s report on industrial production in the month of November.
https://www.howestreet.com/2023/12/could-santa-claus-rally-be-a-good-sign-for-the-new-year-mark-leibovit/
COULD SANTA CLAUS RALLY BE A GOOD SIGN FOR THE NEW YEAR?
Investing.com — U.S. crude inventories declined more than expected last week, the API reported Tuesday, at a time when many are concerns about burgeoning non-OPEC production, pushing global crude supplies into surplus.
Crude Oil WTI Futures, the U.S. benchmark, traded at $68.83 a barrel following the report after settling down 3.8% at $68.61 a barrel to remain on track for its longest weekly losing streak since 2018.
U.S. crude inventories fell 2.3M barrels for the week ended Dec. 8, compared with a build of 549,000 barrels reported by the API for the previous week. Economists were expecting an decline of about 1.5M barrels.
The larger-than-expected draw comes as concerns about growing non-OPEC supply offsetting recent output-cut pledges by OPEC and its allies, OPEC+ amid doubts about whether the cuts will be extended.
The API data also showed that gasoline inventories increased by 5.8M barrels last week, while distillate stocks decreased by 300,000 barrels.
The official government inventory report due Wednesday is expected to show weekly U.S. crude supplies decreased by about 1.5M barrels last week.
Silver Shortage: A Closer Look at Market Dynamics Heading Into 2024 -Investing Haven
The price of silver may not be reflecting the intensifying silver shortage, but it’s a matter of time until the silver supply squeeze pushes the price of silver much higher.
Recent reports from the Silver Institute have sent ripples through the market. Let’s simplify the complexities, focus on key takeaways and what it might mean for the silver market and silver price price going forward.
The topic of silver shortage has been center stage in recent weeks, particularly after the Silver Institute released its later physical silver market data. It evoked a lot of reactions as evidenced by data driven posts on social media.
Let’s review the facts, and add commentary about the market dynamics that go a step further than the data points served by The Silver Institute.
The Silver Institute’s update reveals a decrease in total silver supply due to production losses at major mines, notably the Penasquito mine. On the flip side, non-investment demand has surged, primarily driven by industrial use, reaching an all-time high. Despite slight dips in jewelry and silverware demand, the crux lies in the booming industrial demand, particularly for photovoltaic solar cells.
Janet Yellen Fiddles While America’s Economy Burns – heritage.org
by EJ Antoni
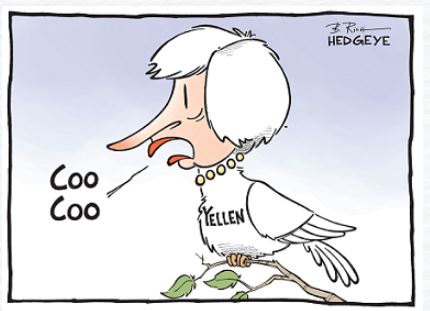
YellenAmerica’s ruling class lives in a fantasy world. Treasury Secretary Janet Yellen recently said the United States economy is not only “doing very well,” but that the nation can “certainly afford” to pay for two wars at the same time: Ukraine and Israel. It’s distressing to realize that the woman ostensibly in charge of the nation’s finances knows nothing about them—and the Treasury’s data prove it.
First, the idea that the economy is doing well is laughable. Inflation has become embedded and is running about twice the Federal Reserve’s 2% target, as well as two and a half times the rate it was when President Joe Biden took office. Last year, inflation reached 40-year highs as prices throughout the economy set record after record.
Under the leadership of Mr. Biden and Ms. Yellen, prices have risen more than 17%, and they continue rising. Inflation has outpaced earnings growth so rapidly that the average worker has lost the equivalent of about 5% of his annual income from the dollar’s reduced purchasing power.
The persistent inflation has now led to higher interest rates, which have raised borrowing costs on everything from mortgages to credit cards—and those cards currently have record-high interest rates. An American family trying to buy a median price home today will pay about $13,800 more per year—for the same house—compared to January 2021 because of inflated home prices and higher interest rates.
CENTRAL BANK ‘HANKY PANKY’
In a 35-minute video, Peak Prosperity’s Chris Martenson explains how central banks can manipulate the prices of all futures contracts in the United States — commodity, financial, and agricultural — through the Chicago Mercantile Exchange’s “Central Bank Incentive Program,” which provides central banks and related institutions with volume trading discounts for trading futures secretly. The CME operates all major futures markets in the United States.
Martenson notes that while the program nominally excludes the U.S. central bank, the Federal Reserve, this exclusion is essentially meaningless, insofar as the Federal Reserve commonly has currency swap lines with other central banks, which presumably can use the “Cent ral Bank Incentive Program” to execute trades for the Fed with the Fed’s money.
As a result, Martenson notes, world markets are hardly markets at all.
This is another issue ripe for investigation by financial journalism should it ever reappear on Earth.
Martenson’s analysis is headlined “Central Bank Hanky Panky” and can be viewed at Peak Prosperity here:
https://tinyurl.com/4ff3pd4m
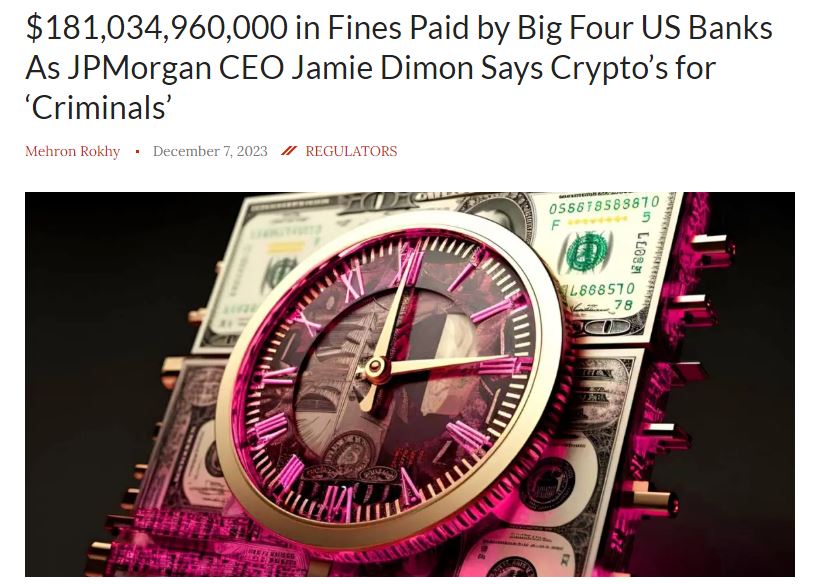
EDITOR’S NOTE: Is the banking crisis in America really that bad? Bad enough that four of the major banks have paid billions in fines since the year 2000. In the wake of this, banks are actively pursuing the transition into the world of digital currency which Jamie Dimon warns is a currency for criminals.
$181,034,960,000 in Fines Paid by Big Four US Banks As JPMorgan CEO Jamie Dimon Says Crypto’s for ‘Criminals’ -Daily Hodl
by Mehron Rokhy
bankHundreds of billions of dollars worth of fines have been paid by the four biggest banks in the US as JPMorgan’s chief executive sounds off against digital assets, saying they are for criminals.
According to corporate misconduct data aggregator Violation Tracker, the big four banks of the US – Bank of America, Wells Fargo, Citigroup, and JPMorgan – have paid a staggering $181 billion worth of fines since the year 2000.
The data unveils that Bank of America has paid a total of 324 fines worth $87.2 billion since the start of the millennium while Wells Fargo has been fined 261 times for a total of $27.5 billion.
Violation Tracker also reveals that Citigroup was found to be in violation 181 times, paying $26.9 billion worth of fines while JPMorgan has been hit with a total of 272 fines worth $39.3 billion.
The Violation Tracker covers a range of civil and criminal banking offenses including foreign bribery, money laundering, corporate tax evasion, securities violations, accounting fraud, price-fixing, employment discrimination and more.
16th AMENDMENT QUESTION BEFORE SUPREME COURT
Imagine receiving a tax bill for the appreciation on your investments, including the equity in your home, before you’ve even sold them. It could happen if the government has its way at the Supreme Court… the justices focused on the question of whether the 16th Amendment’s authorization of “income” taxes allows for the taxing of unrealized gains. It has long been understood that income taxes apply only to realized gains. Ilya Shapiro, “The Wealth Tax You May Already Owe,” Wall Street Journal, December 6, 2023.
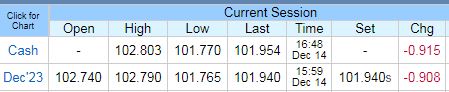
U.S. DOLLAR
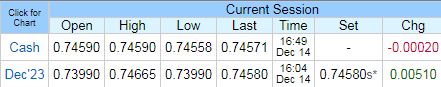
CANADIAN DOLLAR
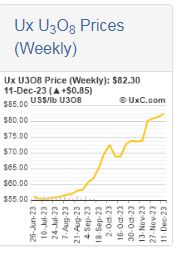
URANIUM – REPORTS ONLY ISSUED WEEKLY
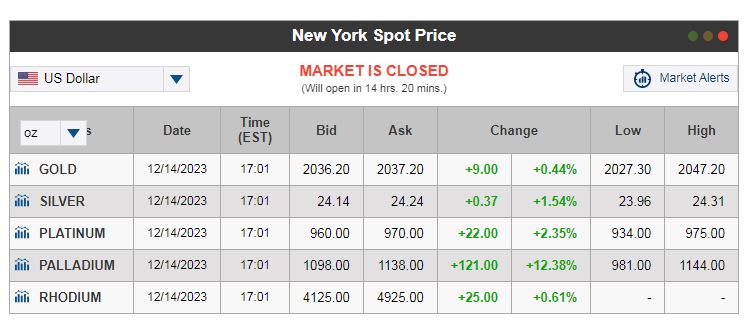
METALS

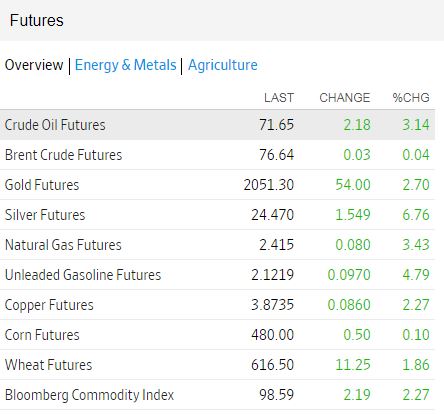
COMMODITIES
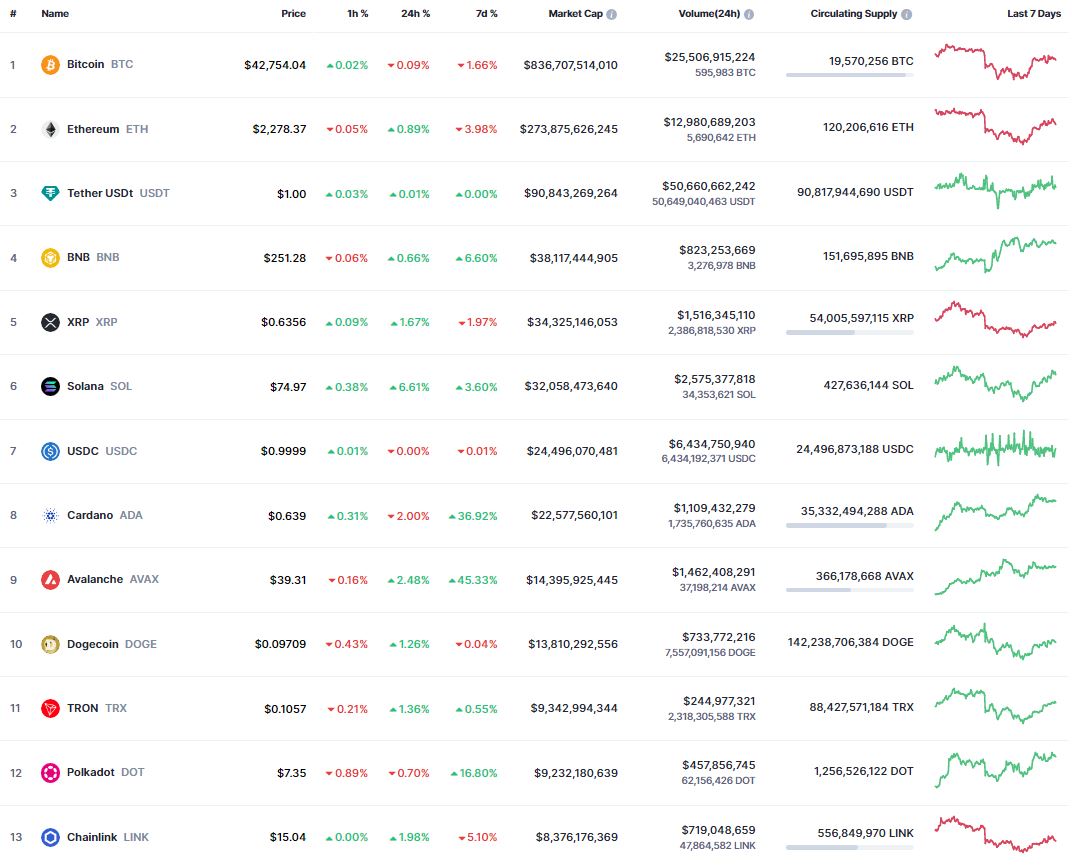
CRYPTO UPDATE AS OF DECEMBER 14, 2023



https://tinyurl.com/2rd9wv52
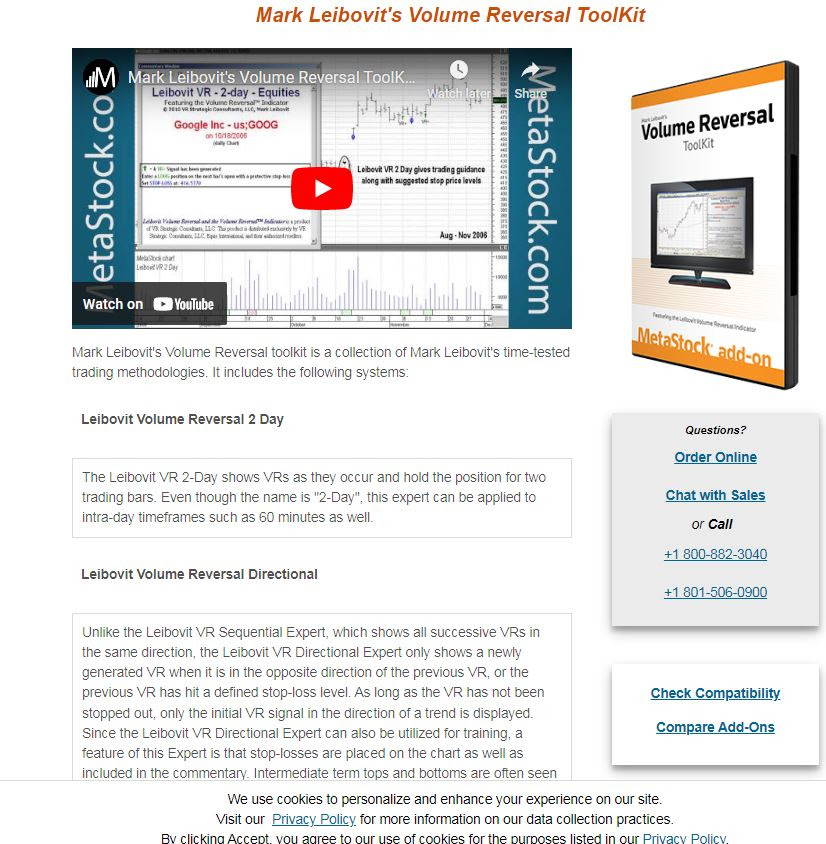
OPPORTUNITY TO ACCESS MARK LEIBOVIT’S PROPRIETARY VOLUME REVERSAL INDICATOR – THIS IS THE ONLY PLACE TO DO IT!
https://www.metastock.com/
FROM 2007 – REP RON PAUL:

IT IS TIME TO REPEAL THE 16TH AMENDMENT – THE ONE THAT CREATES INCOME TAX

THE CASE FOR ABOLISHING THE FEDERAL RESERVE


COME ON, DAD. IT’S TIME TO EAT
DISCLAIMER:
WE ARE NOT FINANCIAL ADVISORS AND DO NOT PROVIDE FINANCIAL ADVICE
The website, LeibovitVRNewsletters.com, is published by LeibovitVRNewsletters LLC.
In using LeibovitVRnewsletters.com (a/k/a LeibovitVRNewsletters LLC) you agree to these Terms & Conditions governing the use of the service. These Terms & Conditions are subject to change without notice. We are publishers and are not registered as a broker-dealer or investment adviser either with the U.S. Securities and Exchange Commission or with any state securities authority.
All stocks and ETFs discussed are HYPOTHETICAL and not actual trades whose actual execution may differ markedly from prices posted on the website and in emails. This may be due internet connectivity, quote delays, data entry errors and other market conditions. Hypothetical or simulated performance results have certain inherent limitations as to liquidity and execution among other variables. PAST RESULTS ARE NOT NECESSARILY INDICATIVE OF FUTURE FORECASTING ACCURACY OR PROFITABLE TRADING RESULTS.
All investments are subject to risk, which should be considered on an individual basis before making any investment decision. We are not responsible for errors and omissions. These publications are intended solely for information and educational purposes only and the content within is not to be construed, under any circumstances, as an offer to buy or to sell or a solicitation to buy or sell or trade in any commodities or securities named within.
All commentary is provided for educational purposes only. This material is based upon information we consider reliable. However, accuracy is not guaranteed. Subscribers should always do their own investigation before investing in any security. Furthermore, you cannot be assured that your will profit or that any losses can or will be limited. It is important to know that no guarantee of any kind is implied nor possible where projections of future conditions in the markets are attempted.
Stocks and ETFs may be held by principals of LeibovitVRNewsletters LLC whose personal investment decisions including entry and exit points may differ from guidelines posted.
LeibovitVRNewsletters.com cannot and do not assess, verify or guarantee the suitability or profitability of any particular investment. You bear responsibility for your own investment research and decisions and should seek the advice of a qualified securities professional before making any investment. As an express condition of using this service and anytime after ending the service, you agree not to hold LeibovitVRNewsletters.com or any employees liable for trading losses, lost profits or other damages resulting from your use of information on the Site in any form (Web-based, email-based, or downloadable software), and you agree to indemnify and hold LeibovitVRNewsletters.com and its employees harmless from and against any and all claims, losses, liabilities, costs, and expenses (including but not limited to attorneys’ fees) arising from your violation of this agreement. This paragraph is not intended to limit rights available to you or to us that may be available under the federal securities laws.
For rights, permissions, subscription and customer service, contact the publisher at mark.vrtrader@gmail.com or call at 928-282-1275 or mail to 10632 N. Scottsdale Road B-426, Scottsdale, AZ 85254.
The Leibovit Volume Reversal, Volume Reversal and Leibovit VR are registered trademarks.
© Copyright 2023. All rights reserved.


[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]